3 Advantages to Financing Your RV

Just like it matters where you buy your RV, how you finance it matters too! 

Picking the perfect RV is no easy task. Across every brand and RV class, some seriously great options are available. From Newmar‘s massive Class A King Aire RVs to the comparatively humble Class B Winnebagos, there’s something for everyone.

Once you’ve picked the perfect RV, you’ve still got one more big choice ahead of you: how to pay for it. While RV newcomers often assume the process is similar to buying a car, reality can be much more complex—especially if you’re choosing a high-end model. 

Given how big of an investment an RV can be, many drivers are tempted to either pay cash out of their savings or secure a line of credit from their bank, which allows them to cover most (if not all) the cost of a new motorhome. However, this isn’t always the best route to take.

Working with your RV dealership’s financing options can have some serious advantages, both in the amount of money you owe and the terms you get for repaying it. Let’s take a look!

Financing an RV Offers More Flexibility in Repayment Terms

As RVs can be individually expensive purchases, they come with many considerations when navigating repayment terms. It’s not unheard of for the loans on some luxury RVs (Class A vehicles especially) to extend over 20 years or 240+ months. That means these loans have more in common with a second mortgage instead of a car loan.

It’s hard to imagine your local bank or credit union offering terms like these. Many likely aren’t familiar with the intricacies of owning an RV, and this can create a whole host of headaches.

Discussing financing options with your RV dealership can also save you the steps of dealing with a pre-approval process, which can translate to serious time savings. Depending on where you would otherwise source your RV financing, it’s easy to miss an entire season dealing with clerical tasks. By contrast, an RV dealership understands how important it is to get you behind the wheel of your new RV as soon as possible.

Financing Also Offers Lower Average Monthly Payments

Working with your RV dealership to figure out financing options doesn’t just translate to more flexibility in your repayment timeline; it can also easily translate to lower monthly payments. As we mentioned above, some RV loans can last more than a decade, which translates to very different considerations versus a regular car loan.

More often than not, these longer RV loans translate to significantly lower monthly payments, sometimes as low as $200! Renting an RV for that much money is considered a steal, so try to wrap your mind around owning one for that amount. 

Even better, drivers can expect to pay a lower average down payment as well. As there are fewer hoops to jump through when you reach out directly to your RV dealer, you can expect a cleaner (and more affordable) close on your new motorhome!

An RV Dealership Will Be Uniquely Qualified to Work With You

If you’re noticing a theme here, it’s that RV dealerships are better equipped to work with the unique needs, costs, and considerations of owning an RV than virtually any other source of financing. 

There’s a really obvious reason for this: RV dealerships know more (and care more) about RVs than other sources of financing!

Beyond perks like lower down payments and more flexibility in choosing a repayment window, you can rest assured your servicer actually understands the intricacies of owning an RV! (That’s not something you can always say for banks and credit unions.) This understanding translates to a better all-around experience. After all, your RV dealership’s goal is to sell you an RV, which means they’re strongly incentivized for finding the best possible financing options for you. 

Our financing office works with drivers to find the best possible options for their unique circumstances. Learn more about the different financing options available at NIRVC.

Living Full-Time In An RV

What Is It Like Living in an RV?

Life looks different on the road. There are plenty of immediate, obvious ways that living in an RV is different from living in a fixed home, but some of the biggest differences can be hard to appreciate until you’re actually behind the wheel. Here are some of the most significant ways that life changes when living in a motorhome: 

Your Pace of Life Slows Down – and That Can Be a Good Thing

RV life operates at a fundamentally different pace than life elsewhere. The best parts of RVing are often found when exploring new places or unusual locales. That’s difficult to do if you’re constantly in “go” mode. Over time, you’ll naturally adapt to a pace that lets you savor your surroundings, which can look pretty different from the hustle and bustle of digital life. 

This naturally comes with a change in how you perceive the world. Instead of frantically counting down the days until Friday, you begin to view each week as a chapter in a larger, ongoing journey. In time, you come to appreciate special events even more because you view them as magical moments in time, not hours in a schedule.

Traveling Means You Get Diverse Experiences From Unexpected Places

RV camping lets you see parts of the country that are easy to miss if you only travel by air. Every state is full of interesting detours, quirky towns and beautiful sights that are best appreciated from the road. 

One of the most liberating aspects of RV travel is that it’s (hopefully) not subject to the same schedule crunch as trains and planes, meaning that you’re free to take your time if a place catches your interest. Veteran RVers will tell you that some of their best adventures come from unexpected places, and living behind the wheel of a motorhome makes you equipped to appreciate them when you find them.

You Meet New Friends – and Plenty of Interesting Locals

While not every person you meet at a campground is going to land in the “birthdays and baptisms” part of your life, you’re bound to make plenty of friends. RVers are a famously friendly crowd, meaning that you’re sure to find good company at almost any campsite that you visit. Over time, you may even start to notice some familiar faces at the different places that you frequent! Social media and RVer groups like AIM Club make it easier than ever to connect with like-minded individuals while attending exciting rallies, outdoor excursions, RV training courses and other fun RV-focused experiences. 

New friendships aren’t always limited to other RVers either. During your travels, you’ll undoubtedly meet plenty of locals, and that provides plenty of opportunities for making new friends! 

You Get a New Appreciation for (and New Definition of) Safety

When your home is on wheels, you quickly learn to appreciate all of the care that keeps it running. You also develop a strong sensitivity to potential safety hazards, and that means thinking about it in a way that suburbanites and city dwellers don’t. As an RV owner, any issues in your vehicle translate to issues with your house, and visa-versa. 

Most home and apartment owners merely have smoke alarms and fire extinguishers to fight fire, but RV drivers will happily opt for something more advanced. A leading example of this is THIA by Proteng, a patent-pending fire suppression system that is heat-activated, minimizing fire damage by eliminating heat at the source. 

Ultimately, It’s About the Little Things

Living in a motorhome allows you to appreciate life from an angle that’s difficult to find anywhere else in the modern world. While you’ll be sacrificing some areas–a fixed routine or consistent access to sushi–you’ll be gaining in just as many others. One of the biggest changes that happens is a newfound appreciation for the little things. 

While an RV trip is ultimately about getting somewhere (like the East Coast or the Grand Canyon), the little moments that happen along the way are often what make it magical: Unexpectedly good food from a local dive; nights spent stargazing free from the light pollution of the city; grilling away the afternoons with newfound friends at a shady autumnal campsite. These small adventures are what make RV life worth it and you’ll come to develop a profound appreciation for them. 

RV life is ultimately about adventure, and there’s no shortage of it to be found on the open road. Sometimes these adventures are big cross-country endeavors, and sometimes they’re as simple as an afternoon of fishing. Either way, living behind the wheel of a motorhome puts you in a unique position to experience – and appreciate – all of the magic that our big, beautiful country has to offer.

If you’re ready to take the next step and learn more about RV living, contact one of our Lifestyle Specialists today!

NIRVC & Endless RVing

Endless RVing recently stopped by our Washington, D.C. location to get THIA by Proteng and RettroBand® installed on their motorhome and filmed a video about their experience.

They’ve partnered with us to offer their viewers 10% off ONE of the following services up to $500 at any NIRVC location through 6/30/2023 with code ENDLESS10:

At the time of service, you’ll need to show the following coupon either physically or digitally.

Endless RVing 10 Percent Off Coupon

Watch the videos below to learn about their experience!

Want to watch more of their videos? Check out their YouTube channel!

RV Generator Selection

RV Generators: A How-To Guide

Modern motorhomes are packed with the latest technology and household conveniences. Items such as washer/dryer laundry centers, dishwashers, entertainment systems featuring multiple HD TVs, residential refrigerators and electric cooktops all require 120 volt AC power – and that’s in addition to the rooftop air conditioners. 

All of these items operate just fine when you are parked and plugged into a campground pedestal that supplies shore power to the coach, but what happens when you are driving or camping at a location that does not have any shore power? 

Many coaches have inverters that will power some devices, such as a residential refrigerator, microwave oven and entertainment systems. But larger AC power loads can’t be handled by an inverter when driving, such as rooftop air conditioners. Plus, dry camping inverters can draw down your battery bank pretty quickly, so you will need to rely on the motorhome’s generator to provide AC power in order to operate these items and to recharge your battery bank.

Generators come in various forms and sizes, so it’s best to analyze what your power consumption needs and particular applications are when choosing the best generator for you. First, let’s understand a bit how generators work…

Portable- Versus Permanently-Mounted RV Generators

Most larger Class A coaches will come equipped with a generator that is permanently installed in the coach. Larger diesel pushers generally have them installed in the nose of the coach and are mounted on a slide-out rail for ease of service. Gasoline powered motorhomes that are of a front engine design will have them installed in a side compartment, or may even be an optional feature.

National Indoor RV Centers blog RV Generator in Class A motorhome

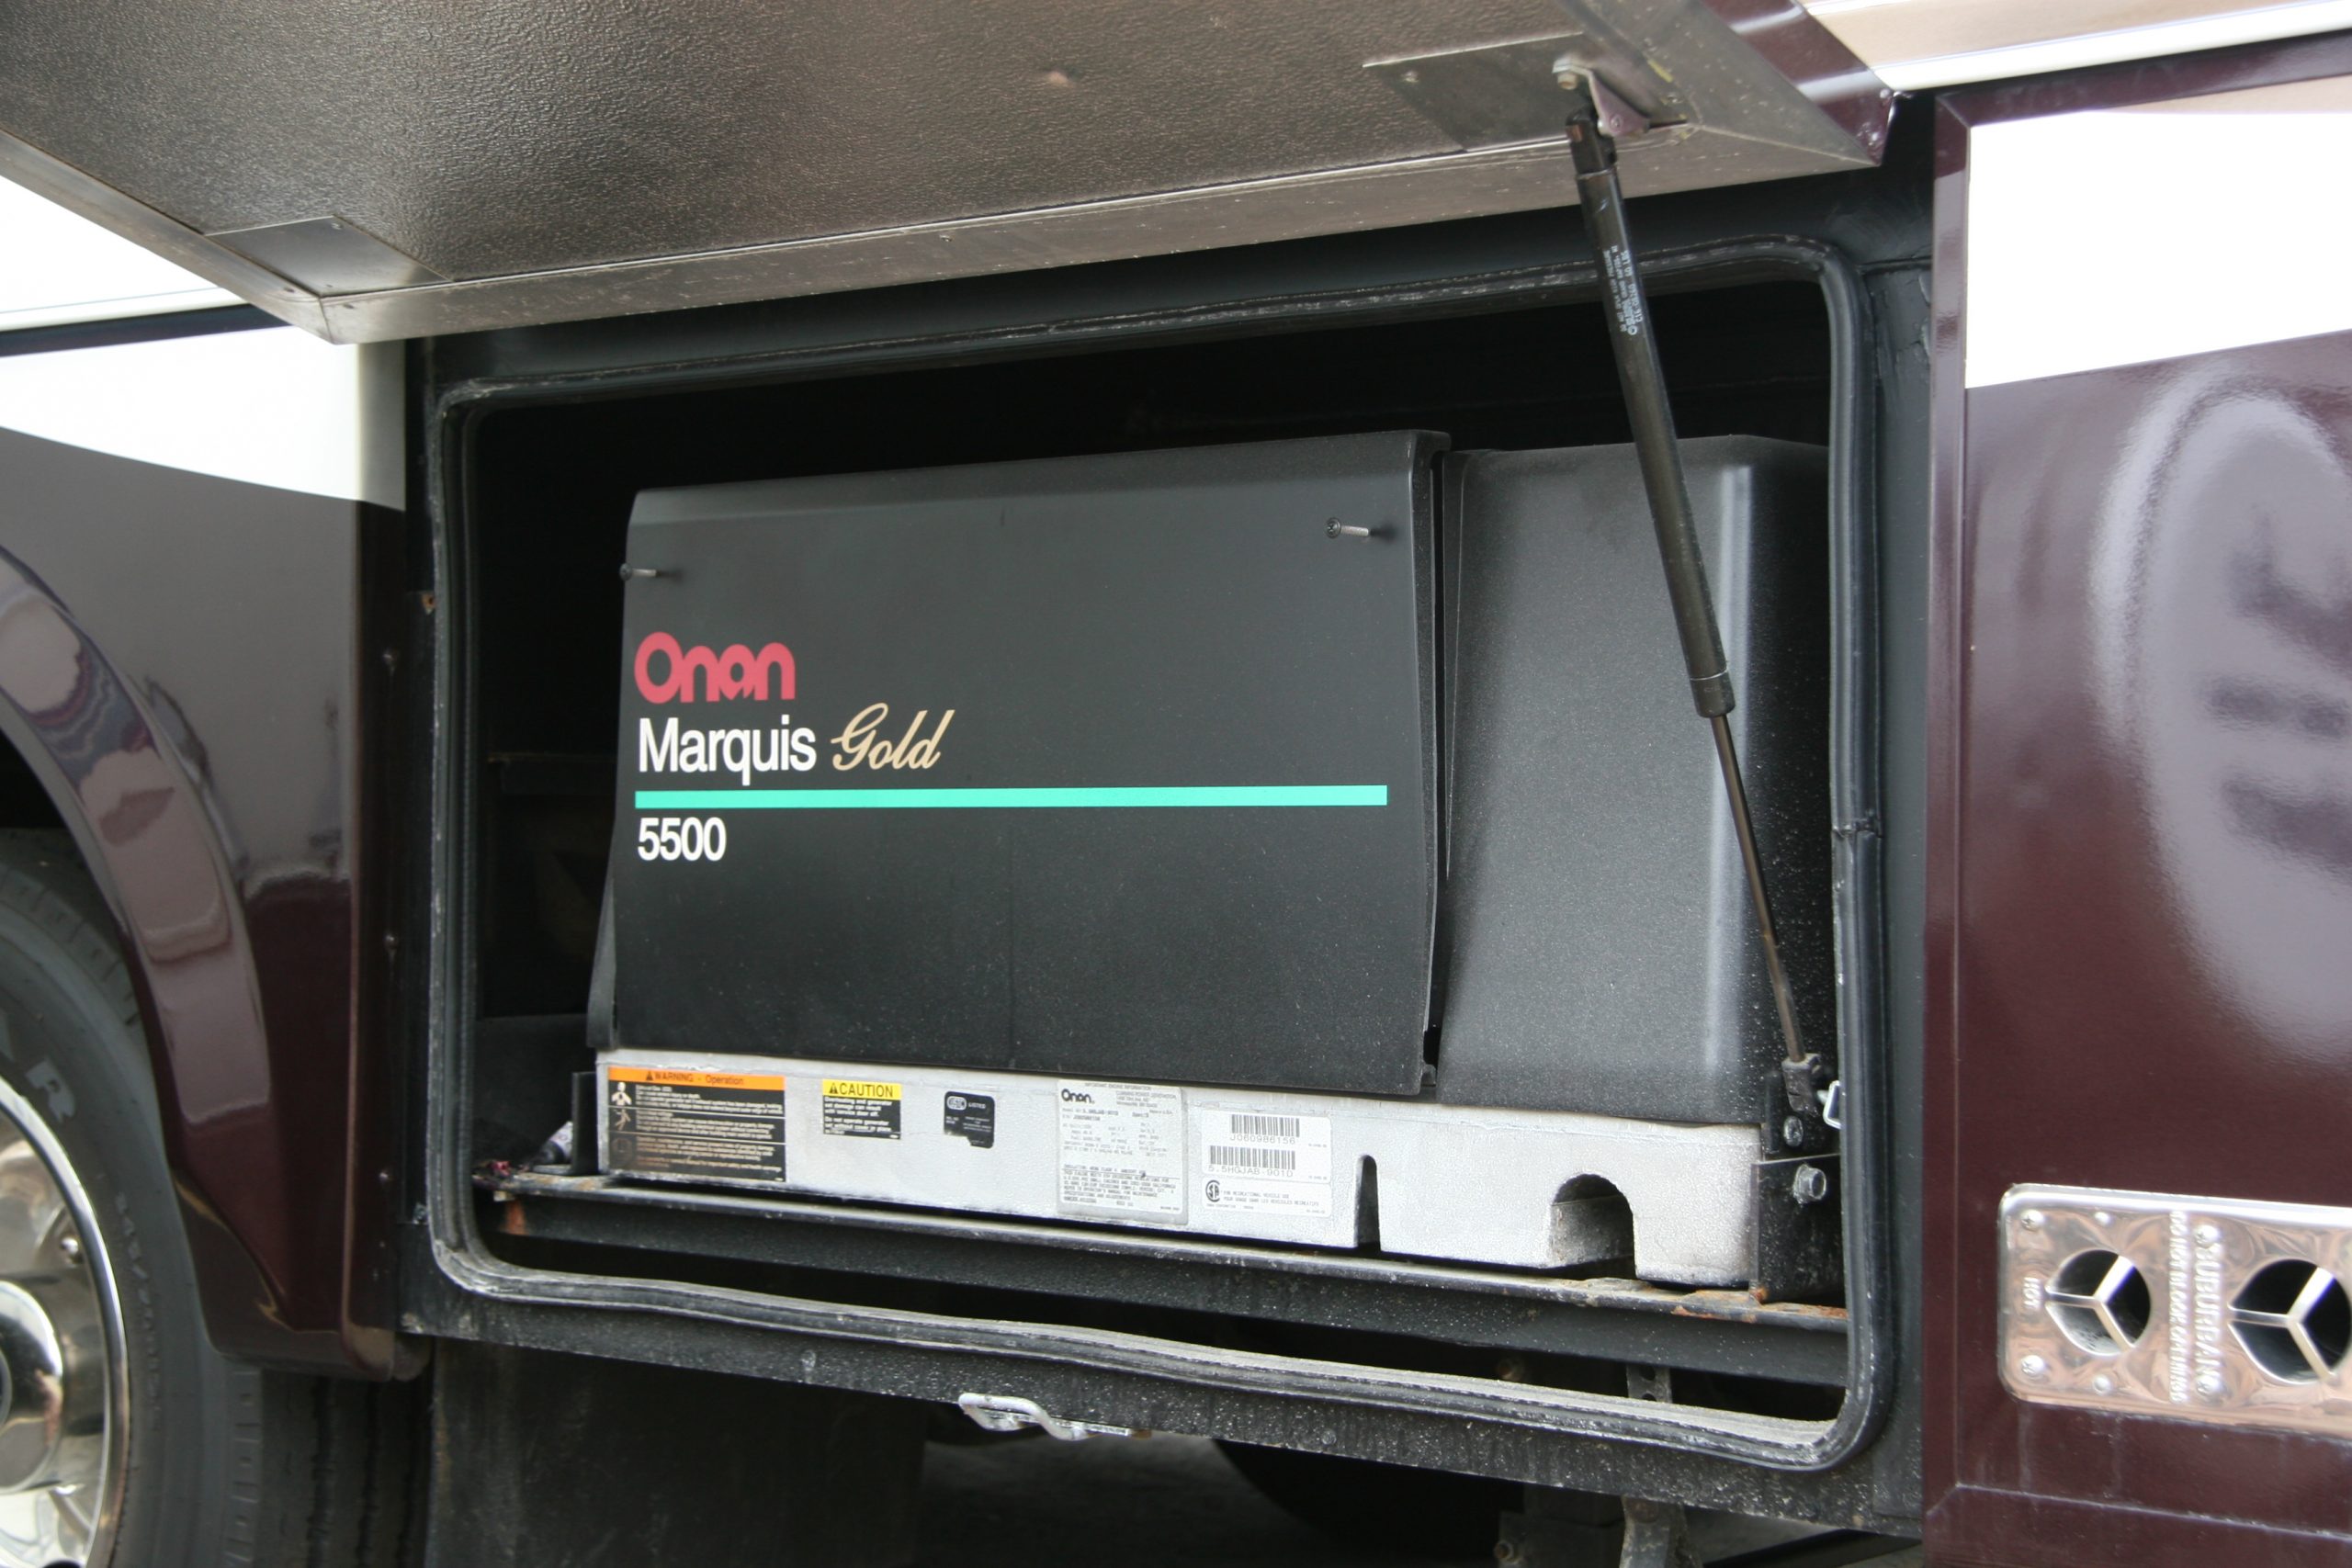
Generators such as this 5500 watt Onan Marquis Gold gasoline powered generator are commonly mounted in a basement compartment on gas powered class A motorhomes.

Installed generators have the benefit of using the same fuel tank that feeds the engine. The output wiring is connected to an automatic transfer switch, making it a simple task to start the generator via a switch in the motorhome’s interior. Smaller Class C and Class B motorhomes are limited on storage, so a generator is often an option not chosen by the buyer, opting instead for more storage space. In that case, a portable generator might be a better choice.

National Indoor RV Centers blog-RV-compact-generators-Class C-Class B motorhomes

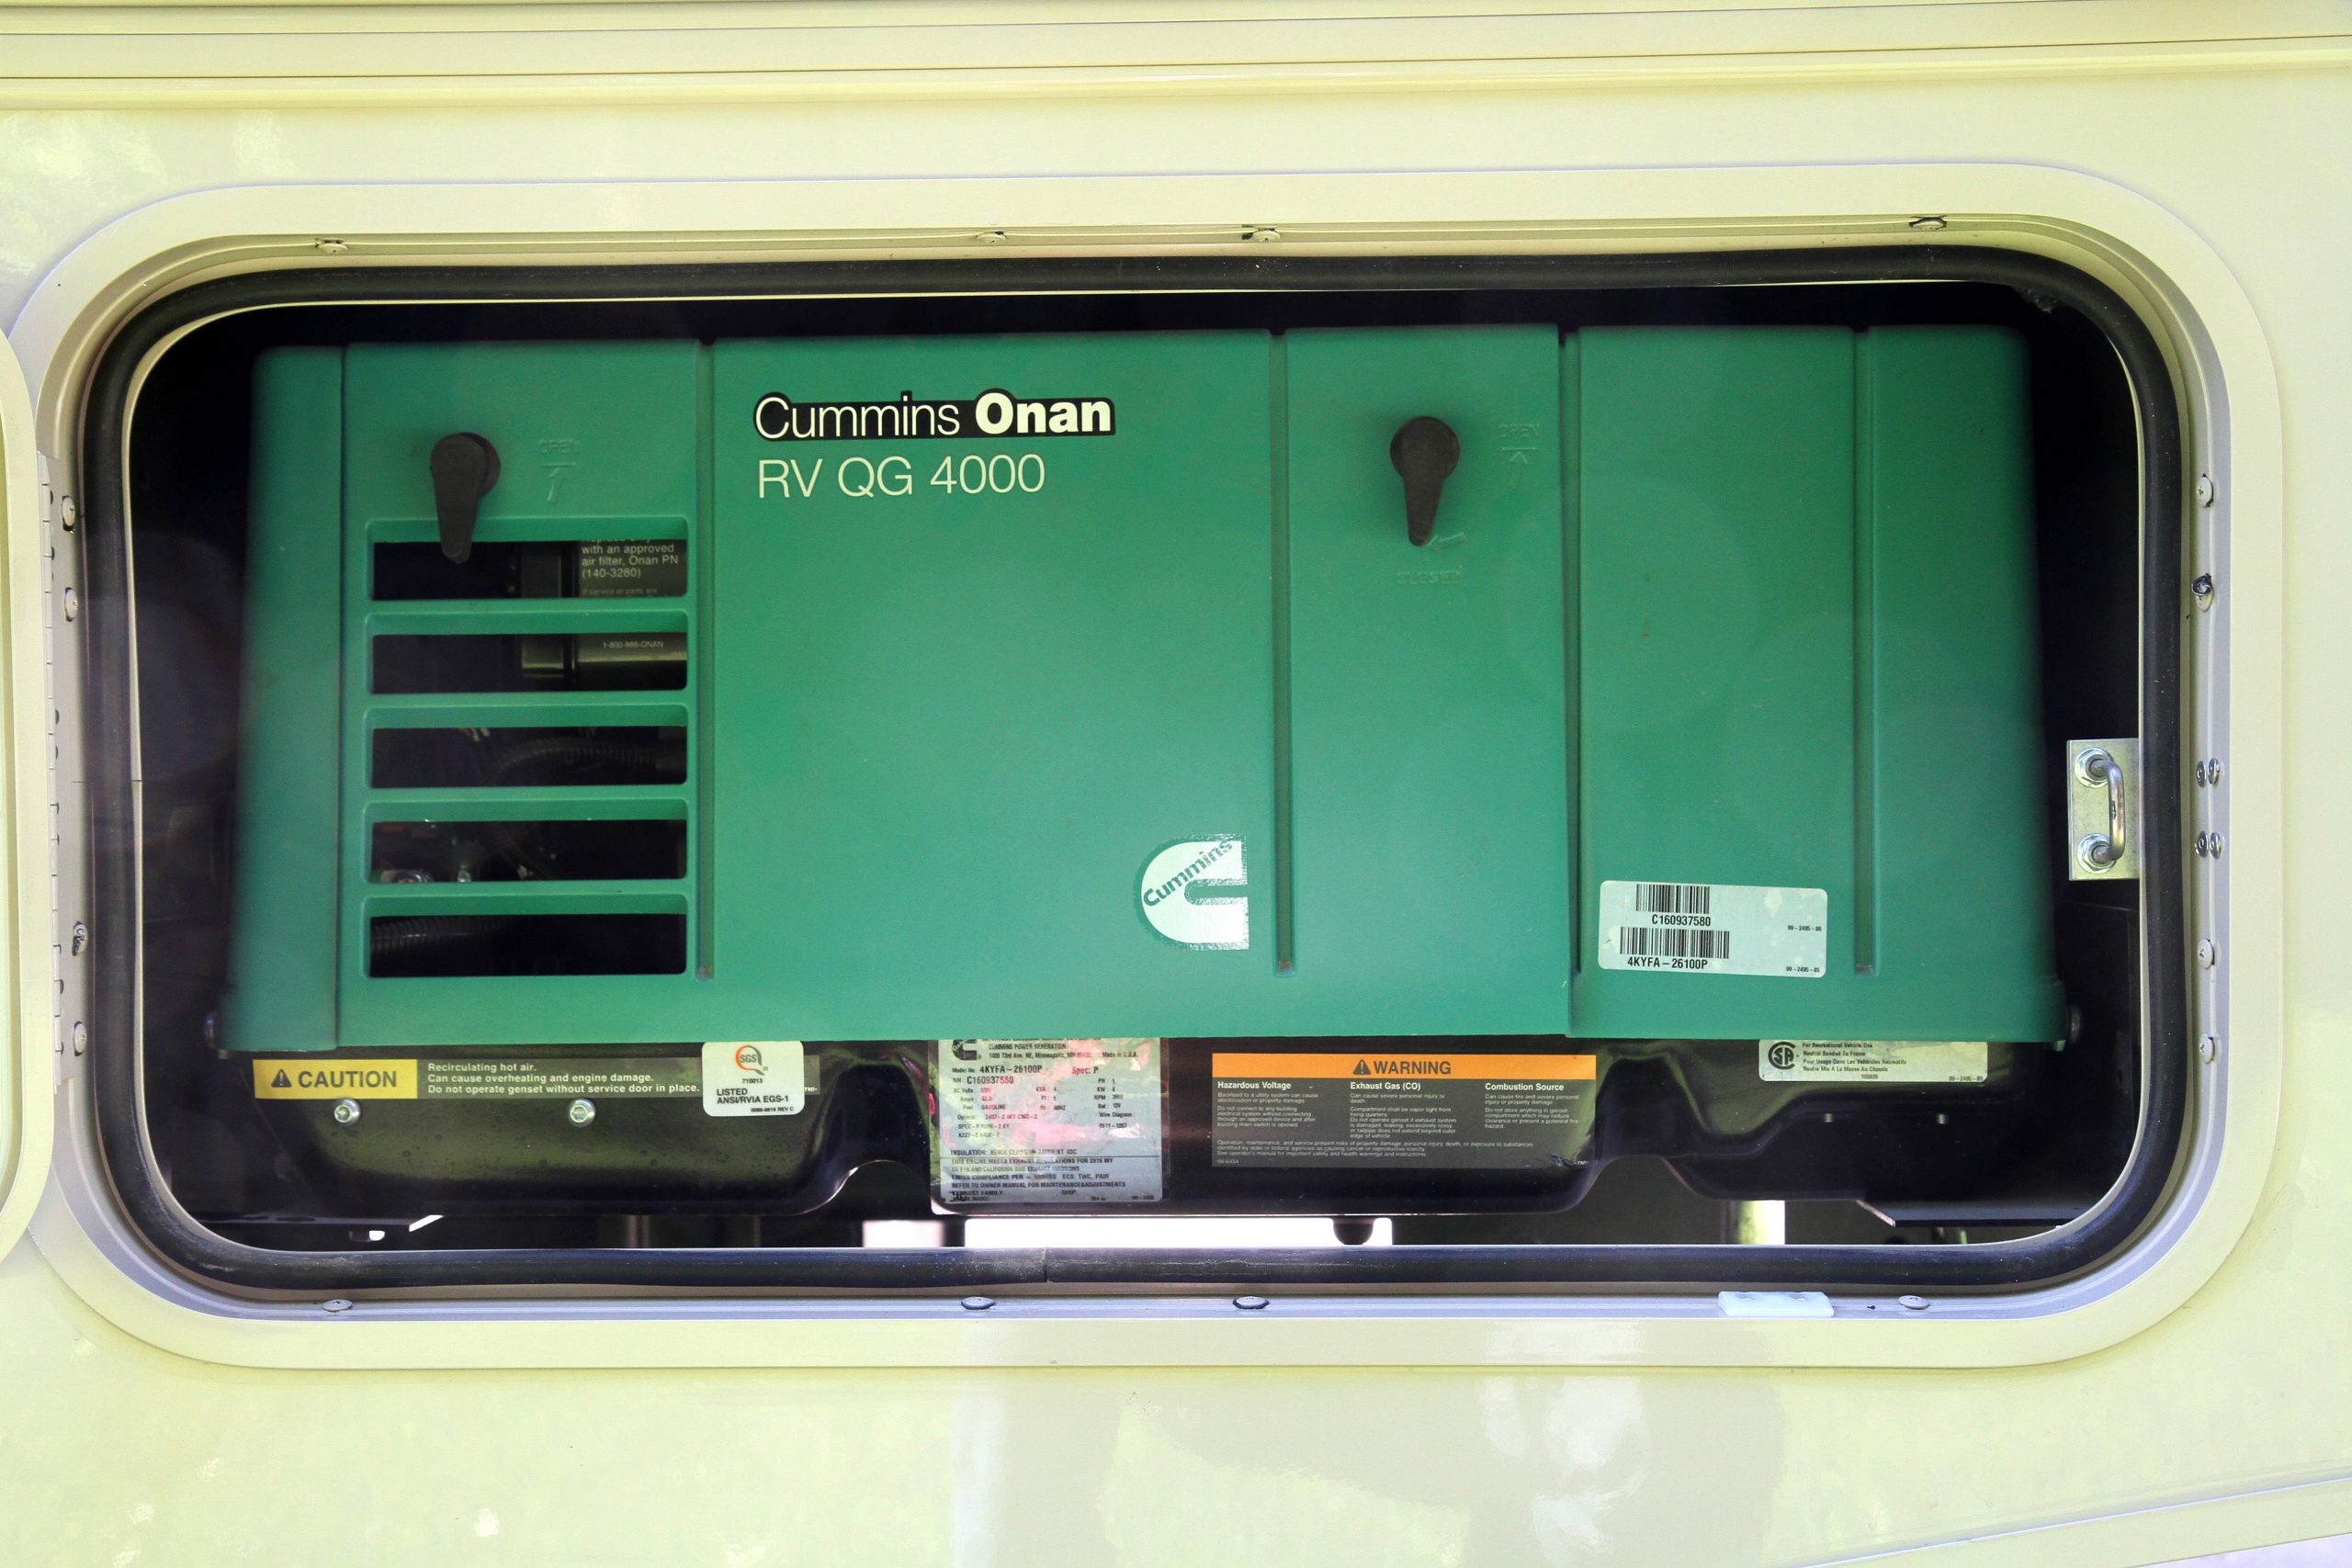
Compact units – such as this 4,000 watt gasoline powered Onan – are typically installed in Class C or B+ coaches where basement cargo space is limited in height.

Portable generators won’t tie up your RV’s basement storage space, but you will have to find some place to carry it, like in the back of a pickup bed. They can multitask, so you can use the generator in other locations without the RV. You can even use it to provide emergency power during an outage at your home. One drawback is that you need to carry a separate fuel supply for the generator, which also requires storage. Weight is also a consideration because the need for horsepower increases as the wattage demand goes up. More horsepower means larger engines that are heavier, making the generator harder to handle.

National Indoor RV Centers-blog-RV generators-portable generator for motorhome use

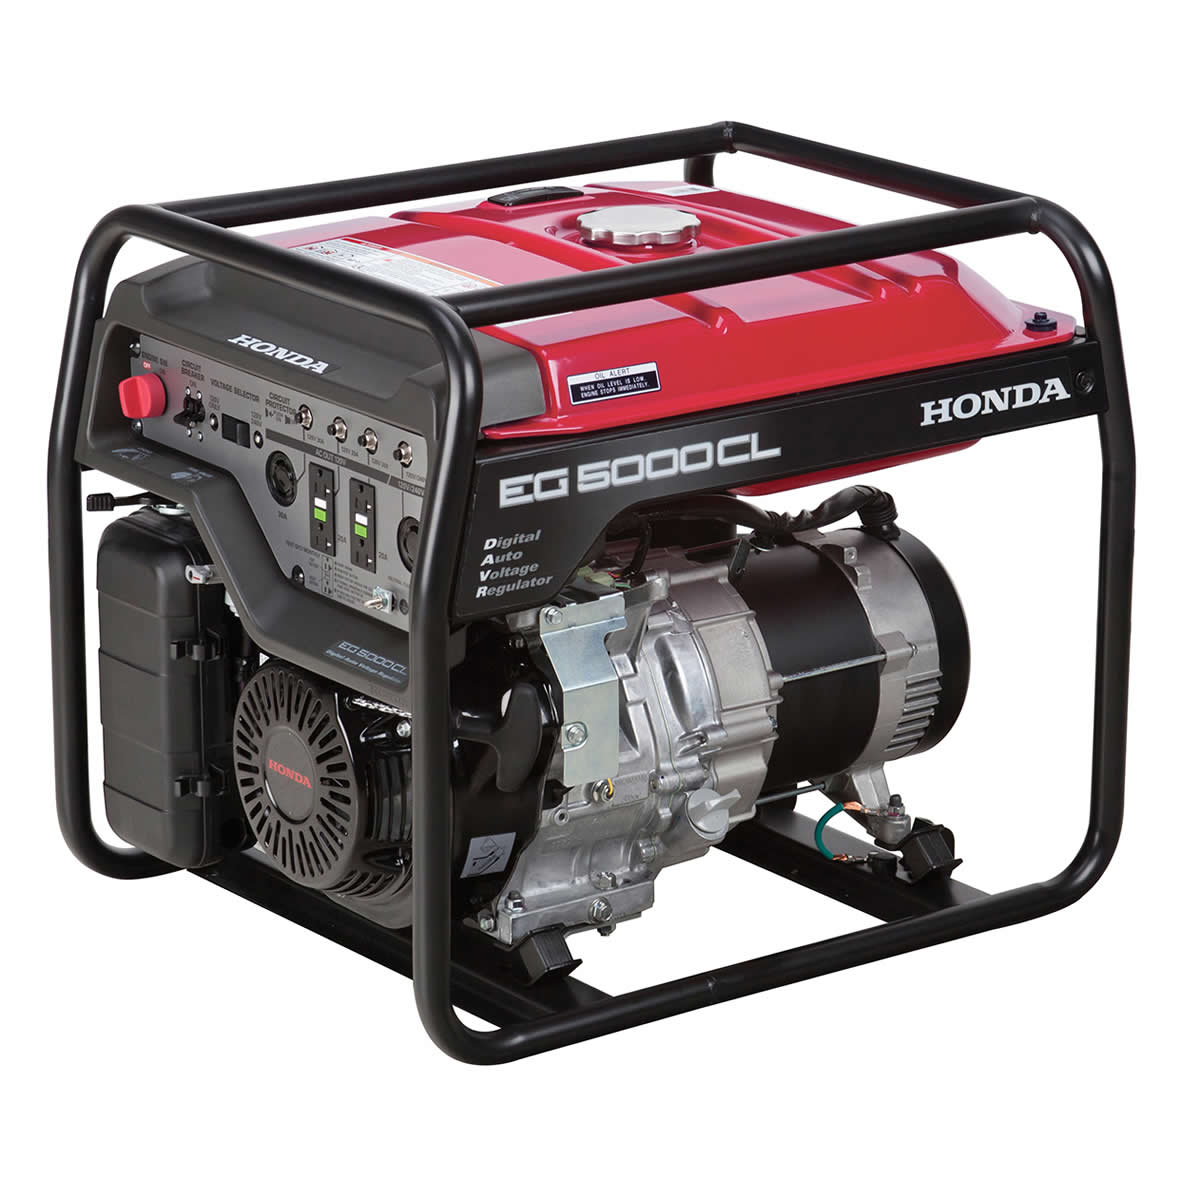
Units such as this Honda 5,000 watt are portable and can be moved by two persons.

Frequency

 Household power in North America is 60 Hertz – which is the measurement of the power’s frequency or wavelength per second – while electrical power in Europe is 50 Hz. Any electrical device designed for use in North America will require 60 Hz power in order to operate. Frequency in a generator is determined by the number of times a magnetic field passes by a generator’s stator winding and receives an induced charge. In a generator with two field coils, the generator needs to spin at a constant 3,600 RPM in order to create 60 Hz power while a generator with four field coils only needs to run at 1,800 RPM.

Most portable generators are of the two pole design to save weight on both the engine and the generator itself. For example – a 3,500 watt generator will require around 8 HP to generate that much electrical power. A typical 8 HP engine will produce that power at peak RPM, which is going to be close to the 3,600 RPM that a two pole generator will operate at. A four pole generator will only need to turn at 1,800 RPM to achieve 60 Hz, but a four pole generator is heavier and bulkier and the engine won’t be able to create its maximum rated power at that slower speed. Therefore, a large engine rated in the 12-14 HP range at 3,600 RPM will need to be used so that 8 HP is still available at the lower 1,800 RPM. The extra weight and size of the larger engine and generator doesn’t make it a good choice for a portable generator but is best suited for a stationary mount where the quieter operation associated with lower RPMs is beneficial.

Split Phase Versus In-Phase:

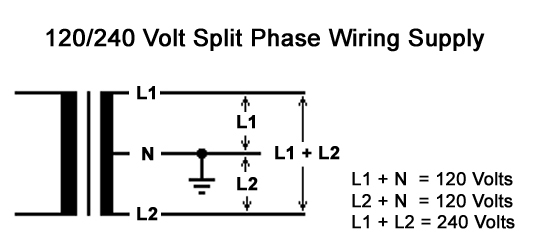
Regardless of whether your generator is a two pole or four pole unit, there will be two field windings that provide power to the receptacles. Each winding is capable of producing 120 volts of AC power at one half of the rated capacity of the generator. These windings can be connected in series to offer 120 or 240 volts in a split phase design, or in parallel to offer only 120 volts in what is referred to as an in-phase design. For example – a 6,000 watt generator has two field coils, each with 3,000 watts of available power at 120 volts. Referring to the graphic below, we can see that there are 6,000 watts of 240 volt power available between L1 and L2. There are 3,000 watts of 120 volt power available between L1 and Neutral, and another 3,000 available between L2 and neutral. 3,000 watts at 120 volts is only 25 amps. Unfortunately, you can’t draw 30 amps on one circuit because the two fields are in series.

National Indoor RV Centers blog RV Generators split phase wiring

The graphic referred to in the text as the Split Phase diagram

The split phase system works fine on larger generators, such as 10,000 watts and up, but has its limitations on smaller units. Many of the smaller units used in RVs do not have 240 volt capabilities, which is fine because 240 volt appliances in an RV are extremely rare except for very high end coaches. In this case, the two windings are placed in parallel rather than series. This eliminates any 240 volt capability but allows for the full 6,000 watts to be available on any one circuit. This is referred to as an in-phase system and is generally used on generators rated at 7,000 watts or less. 

Inverter Generators

Inverters are the opposite of converters. A converter takes 120 volt AC power and converts it to 12 volt DC power to operate lights, water pumps, fans and other 12 volt accessories in the RV as well as battery charging power. An inverter takes 12 volt DC power from the batteries and inverts it to create 120 volt AC power. Small inverters can be used to power an entertainment system while larger inverters can power a number of receptacles and appliances. This means you don’t have to run your generator to keep a residential refrigerator cold while driving and can also operate a microwave and a few outlets. They are helpful because it extends the time interval between times when you need to run the generator to recharge batteries or run larger loads.

National Indoor RV Centers-blog-RV generators-inverter- based-Honda 2200-unit

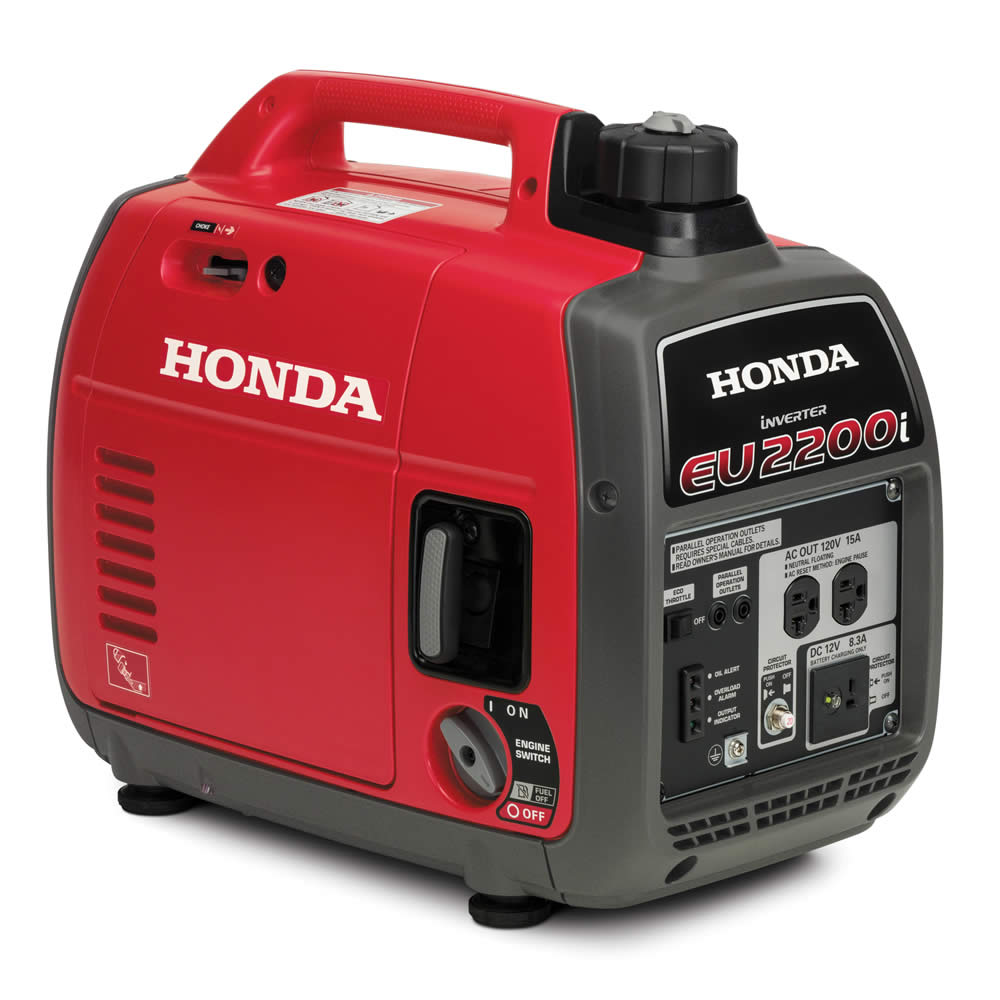
An inverter based Honda 2200 watt unit.

However, inverter technology has also filtered into generators as well. Inverter based generators are popular in some of the small portables, such as the Honda EU2200 series as well as in the Onan Quiet Diesels in the 7KW to 8KW range. In a sense, these generators are not true AC generators, although their eventual output is AC power. They are actually DC generators that send their variable DC output through inverter circuitry built into the generator itself. This eliminates the requirement to operate at a steady 1,800 or 3,600 RPM because the inverter electronics convert the DC power from the generator into 120 volt AC power and establish a 60 Hz frequency electronically. 

A DC generator has no requirement to turn at any given speed because the output power increases as the generator’s speed increases. This allows the generator to operate at a lower RPM under light loads, saving fuel and reducing the noise level. 

As you add more demand for power, such as when an air conditioner starts up, the generator’s speed will increase to raise the power output level, all the while maintaining a steady 120 volt AC power level at a 60 Hz frequency. Inverter based generators also put out fairly clean power with low levels of noise or total harmonic distortion (THD), which is a benefit when powering sensitive electronic equipment. Inverter generators are not found in the larger 10KW  sizes and up because the inverter boards would be large and expensive and generally not necessary with the stability present in the larger diesel generators. However, they are quite popular in the smaller portable models.

Sizing

When selecting the proper size generator, it’s important to remember that wattage is the measurement of true power. A 50 amp shore power supplies 50 amps of 120 VAC power on each leg. “Amps” x “volts” = watts, so a 50 amp shore power receptacle is capable of providing 6,000 watts power on each leg, for a total of 12,000 watts. Therefore, if you want a generator that can match that power, you’ll need a 12,000 watt generator. If you don’t use all of that power, you may be able to step down to a 10,000 watt generator, but the biggest factor is with air conditioning. A coach with two rooftop air conditioners may be able to get by with a 7,000 watt generator, depending on how many other 120 volt accessories you have. But any coach with three rooftop units is going to need at least 10,000 watts.

 When sizing up a generator, you need to consider how your loads are distributed across the breaker panel. A split phase generator can only supply half of the total capacity on each leg, so you have to be sure that your heavy loads are evenly distributed across both legs of the panel. Remember that each leg has a given amount of amperage and on a split phase generator, they cannot be shared. If your loads are imbalanced, you’ll need a much larger generator just to feed one leg while the other leg is not being fully utilized. 

Another consideration is static versus dynamic loads. Lighting and heating elements are static loads in that they always consume the same amount of amps. Dynamic loads are associated with components that have load requirements that vary under different conditions.

Motors are considered dynamic loads because the current draw varies according to how hard they are working – plus, they generally have a startup surge which can be up to three times the running load. Consider the case of an air conditioner. It may have a typical unloaded draw of less than 10 amps, but when it first starts up it will have a surge of in excess of 20 amps as the capacitor start motor starts up against the head pressure in the refrigerant. If the unit was resting long enough, it may settle in to around 10 amps immediately after startup but as the head pressure increases and the unit works hard, it can draw 12-14 amps. Consider that you most likely won’t be starting all three air conditioners at the same time so you don’t need to use the peak starting surge for every unit when calculating how large your generator needs to be. Remember that “volts” x “amps” = watts, so just multiply your amps by 120 to convert to watts in order to determine how many watts you’ll need. 

Following are some examples of typical load requirements:

Air Conditioners 1400-2000 watts
Refrigerator 600-1000 watts
Electric Frying Pan 1000-1500 watts
Electric Stove Element 675-1000 watts
Electric Water Heater 1250 watts
Hair Dryer 500-1500 watts
CRT Television 200-600 watts
LED Television 100-375 watts
Portable Ceramic Heater 750-1500 watts
Toaster 1000 watts
Satellite Dish and Receiver 200 watts
Battery Charger/Converter 750-1400 watts

When sizing your generator, you also need to consider the fact that altitude affects the engine’s ability to create power. Different engines react in varying amounts. An Onan Marquis Gold series of gasoline powered generators will lose 3.5% of power for every 1,000-foot gain of altitude over 3,000 feet. The Onan Quiet Power Diesel 10,000 watt will derate 3.5% for every 1,000’ over 500’ of altitude and it further derates by 1% for every 10oF of temperature increase over 85oF. This equates to a 7,500 watt generator running at 9,000’ of altitude that will only be capable of handling 5,000 watts at that altitude unless the engine has enough excess horsepower to allow for it.

National Indoor RV Centers-blog-RV generators-diesel generator

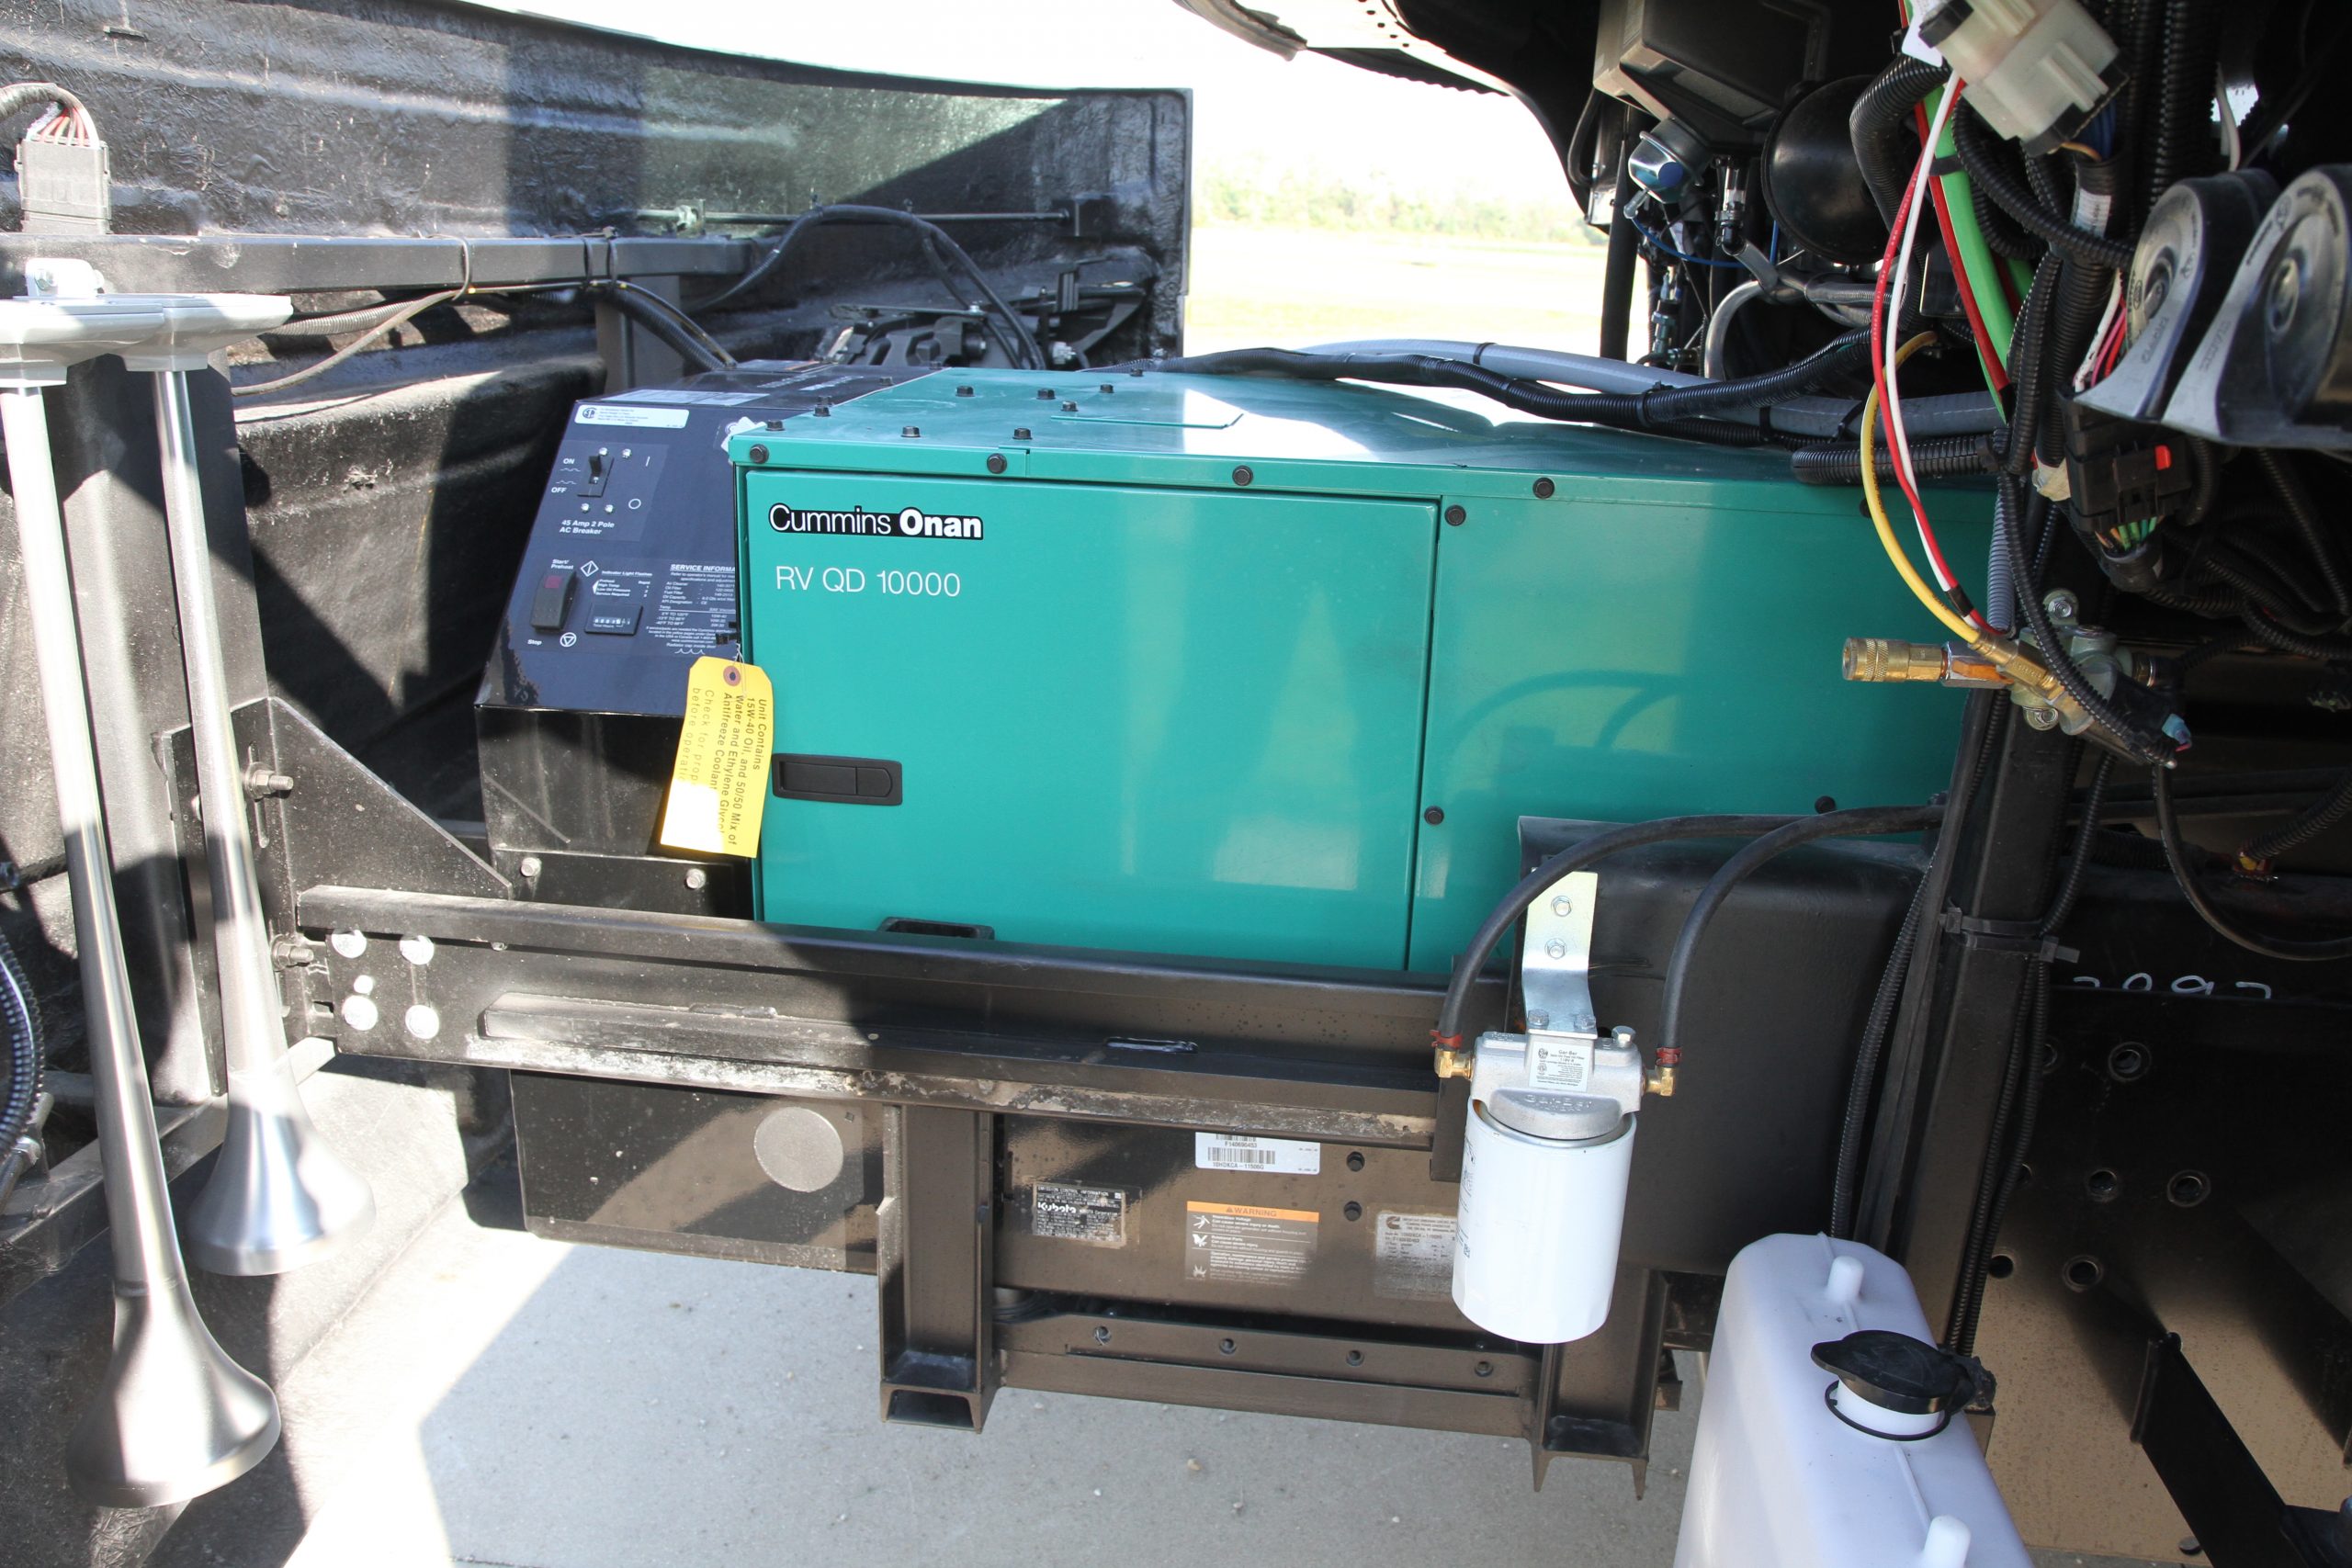
Most Class A diesel pushers have diesel powered generators, such as this Onan 10,000 watt installed in the front cap area of a Newmar London Aire are placed on slide-out rails for ease in service access.

Diesel engines are pretty much capable of handling the fuel injection requirement at higher altitudes but carbureted gasoline powered engines will have issues with running rich due to lack of air. Some generators, like the Onan Marquis Gold series, have a mixture adjustment on their carburetors. You can adjust the fuel flow with a lever to lean the engine out when operating at higher altitudes. But be sure to reset it to the full rich position when you return to the flatlands or else you run the risk of burning valves by running the engine too lean.

Armed with this information, you should be ready to select the best generator for your RV lifestyle. Be sure to include your generator when you have your RV tech perform scheduled maintenance on your motorhome. Taking care of it will ensure it will take care of you when you need it.

RVs, the Economy and You! SVB…Are Banks in Trouble?

In the latest edition of this popular video series on the state of the current economy, Brett Davis, President and CEO of National Indoor RV Centers, explains the factors that led to the Silicon Valley Bank collapse and how it affects RVers, businesses, and the global economy.

Greetings National Indoor RV Centers family of customers and friends.

Since my last video a year ago, when the Fed Funds rate was hovering right at zero, the Federal Open Market Committee has raised the Fed Funds rate 9 times to its current target range of 4.75% to 5.00%. As the saying goes: whenever the Fed hits the brakes, someone goes through the windshield. We all know it. The fed knows it. We just never know who it’s going to be until it happens.

In the wake of all these rate increases by the Fed, I was preparing to share my thoughts on the current state of our economy and the RV market, and where I suspect they are both headed in the future.  

However, I have just returned home from a marathon of back to back to back motorhome rallies in Georgia, where for three weeks the questions posed to me about Silicon Valley Bank, and how sound is our banking system, were relentless. And, to be completely transparent, it wasn’t just the plethora of questions I received during my three weeks of rallies which piqued my interest in the failure of Silicon Valley Bank, or SVB for short. I was already following SVB with both intrigue and concern. Having owned a bank years ago, I was following SVB with intrigue, because it wasn’t your traditional bank. But, I was also following it with some concern, because I’m a limited partner in one of those venture capital funds who did all their banking with SVB. Needless to say, for all those reasons I called an audible to, and decided to share my musings on SVB and our banking system, before sharing my thoughts on the economy and the RV market.

Think of a lofty Jenga tower when discussing complex systems like our banking system. Eventually, one ever so slight miscalculation, one puzzle piece too many, and fatality strikes.

“Eventually” is the key word. Exactly which puzzle piece will do it, we can’t know ahead of time.

But, before the tower collapses, each puzzle piece forms points of instability. Small weaknesses where a failure could begin. Sooner or later, it will be one puzzle piece too many. But, no one knows when, or which piece, will be “the big one” which brings the whole tower down.

These points of instability seem to be piling up lately. Last October, the UK had a brief bond crisis when some budgetary changes revealed rather questionable pension fund activities. Then the bankruptcy of crypto exchange FTX showed how supposedly “trustless” assets can require a lot of trust.

During the second weekend in March, we witnessed the second and third largest bank failures in US history: Silicon Valley Bank and Signature Bank. And yes, several other banks, including First Republic and PacWest, look to be very shaky as well. These banks have similar features to SVB, as well as exposure to Crypto based businesses. However, I also think these banks are very unique. Unicorns if you will. I don’t believe you can paint the current 4,844 FDIC insured banks in our country with the same brush as these banks. Nor do I believe they are representative of the contagion which affected our entire financial system back in 2008. Let alone any contagion which would impact the RV industry whatsoever.  

Fortunately, regulators responded swiftly to stabilize both situations. Personally, I believe 99% of all banks are just fine, but we should all be paying attention to make sure our bank isn’t in the 1%, because important things are happening.

And no, not for a minute do I think this is 2007/2008 all over again. But, it’s also not nothing.

Let’s start with what we do know. We know SVB had problems with both their assets and their liabilities.

It’s important to remember, whenever we deposit our money into a bank account, we are really lending our cash to the bank. It truly is a loan transaction, with us as the lender and the bank as the borrower. In fact, our deposits appear as liabilities on the bank’s balance sheet.

This is how banking works. In its simplest terms, the bank borrows money from us, and then lends it to someone else. If all goes well, the bank profits from the difference between the interest it pays its depositors, and the interest it receives on the loans it makes.

Those loans support small businesses, they help consumers buy cars, homeowners buy their dream homes with mortgages, and a whole lot more. Banks also loan money to the federal government by purchasing Treasury securities. They don’t yield as much as a loan, but they are also lower risk. However, they are not zero risk, as we’ll see in a minute.

Running a bank is truly a balancing act, because the bank’s assets, which are really loans, and the bank’s liabilities, which are really deposits, have different maturities. People can demand their money back at any time, but the bank can’t call in its loans, at least not very quickly. It works only because most people leave their balances in place most of the time. This is where having a loyal, diversified depositor base really helps reduce the risk profile of a bank.

The absence of a loyal, diversified depositor base proved to be a real problem for SVB. Most of SVB’s deposits came from a relatively small group of venture capital firms who “recommended” to the startup companies they funded to keep their cash balances at SVB. The nature of these startup companies’s deposits added an additional degree of difficulty to SVB’s balancing act beyond a highly concentrated depositor base controlled by a handful of Venture Capital funds.

Startups are just that… startups. Companies with an idea, but no capital to bring their ideas to fruition. Venture capital funds provide their startups with all their projected cash needs right up front. Meaning, on day one the startup has a pile of cash, operating expenses, and no revenues. The hope is revenues for their idea, their new product, will grow to meet and exceed their operating expenses, and thereby start producing a profit. It’s not uncommon for this to take years. It took over nine years from its founding for Amazon to turn its first profit. In Amazon’s 58th quarter of existence it finally made a profit larger than its previous 57 quarters combined. That’s 14 years and two quarters after startup. Here are a few more companies we all know. It was 5 years before FedEx was able to turn a profit, and 7 years before ESPN became profitable. From its founding it was 17 years before Tesla made its first dime. From their founding to profitability startup companies are burning through the cash they were funded with at startup. Venture capital funds project what they believe the burn rate of their startups will be until they reach profitability, and assuming their ideas prove to be economically viable, they fund their startups with that capital right up front, and in turn those startups deposit their funds in whichever bank their sponsoring venture capital fund recommends.

In addition to their highly concentrated depositor base of venture capital funds, SVB had to also contend with the “burn rate” of the startups these firms had funded, which now comprised their depositor base. Clearly this was far from a traditional depositor base for a bank.

As a part of the macro slowdown in 2022, which slowdown was the intended result of the Fed raising interest rates, the burn rates of these startups actually accelerated. SVB poorly forecasted the accelerated burn and the resulting draw-down needs of their depositors. Which, resulted in SVB not having the liquidity to pay them all.

What SVB did have was a lot of longer-term Treasury bonds and mortgage-backed securities it had purchased when their deposits ballooned in 2020 and 2021. Which, was before the Fed started raising interest rates in March of 2022. If you remember from my RVs, the Economy and You! Update 2, Part 1 video from last year, when interest rates rise the market value of bonds falls. Which isn’t a problem if you can hold the bonds to maturity. However, it can be a big problem if you need to sell them in order to cover your depositor’s withdrawals.

Rising interest rates put SVB in a tough spot, which got tougher as depositors withdrew their money in the weeks leading up to SVB’s failure on 3/10/23. Here is an excerpt from my video last year which is truly appropriate in SVB’s case.

Insert 0:57 to 1:11 from RVs, the Economy and You! Update 2, Part 1

SVB’s failure started gradually with by poorly forecasting their depositor’s burn rate, which is best explained by SVB’s former President in his letter to investors: 

“While Venture capital deployment has tracked our expectations, client cash burn has remained elevated and increased further in February, resulting in lower deposits than forecasted. When we see a return to balance between venture investment and cash burn – we will be well positioned to accelerate growth and profitability,” noting SVB is “well capitalized.”

SVB was forced to sell some of their Treasuries and Mortgage-Backed Securities in order to fund these withdrawals. With each sale of their treasuries SVB was forced to recognize the inherent market losses created by rising interest rates over the past year.

SVB’s portfolio of Treasuries was yielding an average 1.79%, which was far below the 10-year Treasury yield of around 3.9%. These sales forced SVB to recognize a $1.8 billion loss, which it would need to replace through raising more capital by selling more shares in the bank.

Late in the day on Wednesday March the 8th, SVB spooked investors and depositors with a belated attempt to raise additional capital by announcing the sale of $2.25 billion in common equity and preferred convertible stock to replace the capital it had just lost. SVB’s stock ended the day down 60%, as investors fretted further deposit withdrawals may push the Bank to raise even more capital. 

In what will probably turn out to be the most ill-advised conference call in the history of banking, in a failed attempt to head off a run on his bank, the President of SVB held a conference call with the bank’s twelve largest Venture Capital funds at 11:30am PST on Thursday, March 9th. The purpose of his call was to reassure the bank’s largest depositors their deposits were safe, the bank was healthy, and in not so many words he essentially conveyed the bank could withstand anything…except a run on the bank.

Well, as it turned out, the dozen Venture Capital funds were calm, until SVB’s President instructed them to remain calm three times during the call. Within 30 minutes of the call ending, $42 billion of withdrawal requests hit the Bank’s wire desk. That bears repeating. $42 billion of SVB’s $175 billion in total deposits had just requested their money back! The Bank did manage to fulfill the $42 billion in withdrawal requests, and then they promptly closed the bank early. Which, led to the lines of people we’ve all seen pictures of, as Venture Capital funds instructed their companies to go to the bank to withdraw their money in person.

However, Thursday’s $42 billion in withdrawals pales in comparison to what was about to happen on the morning of Friday March the 10th. Michael Barr, vice chair for supervision at the Federal Reserve testified before the Senate banking Committee, and I quote:

 “That morning, the bank let us know that they expected the outflow to be vastly larger based on client requests, a total of $100 billion was scheduled to go out the door that day.”

Consequently, SVB never opened on Friday as the combined withdrawal figure of $142 billion represented a staggering 81% of SVB’s $175 billion in deposits. Think about that. $142 billion in withdrawals in less than 24 hours, which is why the FDIC jumped in. The dizzying pace at which money left SVB shows just how quickly bank runs can happen with the technology of today’s world. Social media heightens panic, and online banking allows for quick transactions.

The speed at which SVB failed is unique. And, to highlight this point, think about this. 538 banks have failed since 2008, and yet few of us knew about them. Life went on as normal. But, $142 billion in under 24 hours severely limited the FDIC’s options and brought with it a lot of publicity. 

I readily admit, I wasn’t a fan of how the Fed handled the bailouts of banks in the 2008 crisis, but I do believe they did it correctly this time. While you may or may not be a fan of SVB’s customers (tech startups) they were and are very important to the US economy. We need them! I believe they are truly “systemically important.” The FDIC gave SVB customers full access to their deposits, so they made payrolls and life went on. I believe this was appropriate, and please let me explain.

The World’s five most devastating financial crisis are the Credit Crisis of 1772, the Great Depression of 1929 to 1939, the OPEC Oil Price Shock of 1973, the Asian Crisis of 1997, and the Financial Crisis of 2007/2008. I have lived through three of those five crises, but the Financial Crisis of 2007/2008 really stands out, and not because it’s the most recent. It stands out because of how it was handled.

The Troubled Asset Relief Fund, better known by its acronym TARP, was instituted by the US Treasury following the Financial Crisis of 2007/2008. TARP stabilized our financial system by having the government purchase mortgages backed securities and bank stocks. That’s right, the government purchased equity in banks and other financial institutions. From 2008 to 2010 TARP invested $426.4 billion in banks and other financial institutions and recouped $441.7 billion in return. But, part of what made TARP so controversial was the shareholders were not wiped out, nor were any people fired. This is why I wasn’t a fan of how the Fed bailed the banks out in 2008.

But, this time around, unlike 2008, the FDIC did wipe the shareholders out, and they did fire the senior management of the bank. When you mess up that spectacularly, you should be fired! And honestly, I will say the same thing about Federal regulators and their ridiculous stress tests. It is hard for me to believe they could have truly been that blind!

As pointed out in the Wall Street Journal on March 15th, even if midsize banks had been subjected to the same scrutiny as large banks it’s very doubtful it would have prevented SVB’s failure. Why? Because the tests failed to encompass the very scenario which ultimately led to SVB’s demise… large and rapid increases in interest rates. 

In its February 2022 Stress Test Scenarios, the Fed’s “severely adverse scenario” asked banks to assess their riskiness over a three year horizon assuming the 3 Month Treasury stays near zero percent while the 10 Year Treasury declines to 3/4 of 1% during the first three calendar quarters of 2022. Think about that for a minute. In February 2022, the Fed instructed banks to assume zero percent interest when creating their worst-case scenarios, and then starting the very next month in March of 2022 the Fed promptly raises rates five times to 4.5% interest by the end of 2022. The biggest rate increase in a single year since 1980.

Then in February of 2023, when the 3 Month Treasury was already at 4.5%, the Fed shockingly instructs banks to assume the 3 Month Treasury falling to near zero percent by the 3rd quarter, and the 10 Year Treasury falling to 1/2 of 1% by the 2nd quarter in their worst-case scenarios. This truly makes reason stare! Is this how anyone who was warm and had a pulse would project and prepare for a worst-case scenario? By pretending they’re really not raising interest rates? Is this truly how they’re going to regulate our banks? Talking out of both sides of their mouths? Throughout my business career I have always believed no enemy is worse than bad advice.

The Fed’s 2023 severely adverse scenario assumptions bore no relationship to reality. Do the Fed’s bank regulators not talk with each other? Or, at a minimum at least read about what is going on with their own monetary policies? They have been raising rates for a year! The regulatory executives who somehow managed to overlook this should be fired just like the senior management of SVB was. But, we all know that’s not going to happen. Passing additional laws and regulations isn’t going to help if the regulators are incompetent. There were more than enough laws and regulations to have prevented this. In my opinion, firing the senior management at SVB is just a start in cleaning house.

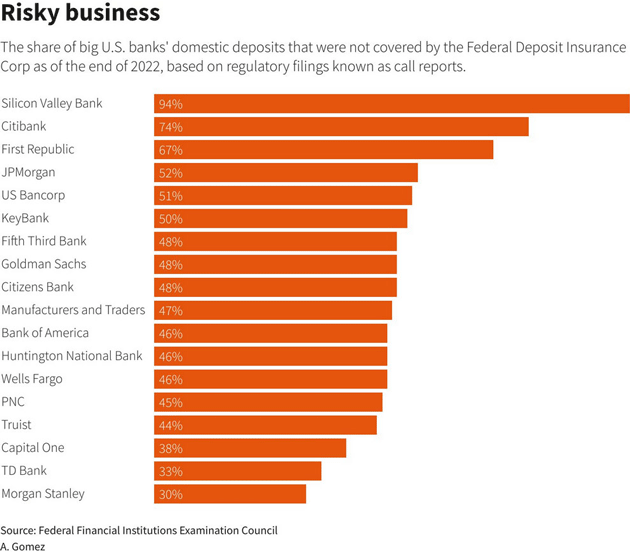
Moving on, I don’t know whether this is fascinating, or truly troubling, but 94% of the deposits at SVB were above the $250,000 FDIC insurance limit, and thereby uninsured.

The $250,000 insured amount was certainly no secret. It is plastered all over bank walls and appears in almost every account document anyone signs. It was crystal clear larger balances were at risk if the bank failed. But, SVB depositors, some of the most sophisticated investors on the planet, simply didn’t seem to care, or believed the limit didn’t apply to them. As it turned out, it didn’t.

Many, if not most, banks offer an Insured Cash Sweep, or ICS service. I know all our banks offer it. ICS accounts extend FDIC insurance by breaking up large cash deposits and then distributing the smaller amounts to multiple banks. ICS accounts simply allow businesses access to FDIC coverage above the standard $250,000 limit. It’s a safe and simple thing to sweep excess amounts, and bring them back in as needed to clear checks. In today’s world, keeping millions of uninsured dollars in the same bank just makes no sense. Yet, it was very common at SVB. And, it wasn’t just SVB. Even our largest banks have more uninsured than insured deposits. And yes, from the chart you can see how SVB led the way with 94% of their deposits being uninsured. 20% more than the next closest bank, which happens to be the international behemoth Citibank. But, let’s put this into perspective. Citibank has 673 locations in the United States and 1,800 branches scattered throughout 160 other countries versus SVB with just 17 branches. I can easily understand why depositors in other countries would care far less about the FDIC insurance limits than our domestic depositors. My point, SVB was a unique bank. It was a unicorn that wasn’t representative of our banking system, or the contagion which affected our entire financial system back in 2008.
US-Banks-Domestic-Deposits-Reuters

Source: Reuters


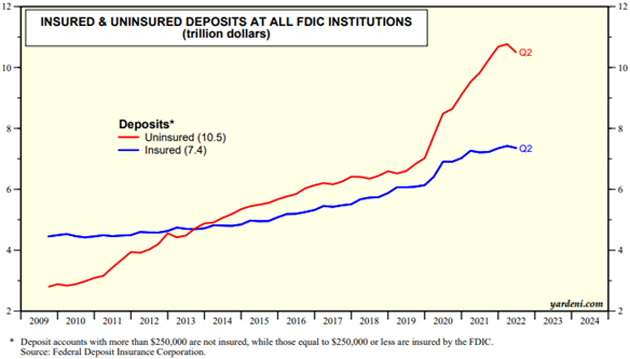
These excessively high uninsured balances haven’t always been the case. Look at this chart from Yardeni Quick Takes comparing insured and uninsured deposits for all US banks.
Insured-and-Uninsured-Deposits

Source: Yardeni QuickTakes


With the current $250,000 deposit insurance limit, US banks had $10.5 trillion dollars in uninsured deposits halfway through 2022 versus only $7.4 trillion insured. In fact, a majority of deposits have been uninsured for a decade now, but notice how the line bends sharply upward in 2020. Why? Well, it’s because it coincides with the Fed’s stimulus, plus all the various COVID fiscal programs. However, there was, and there is still nothing requiring people to keep all that money in banks.

This certainly seems like a problem to me. In the case of SVB, regulators used a “systemic risk” emergency clause to cover otherwise uninsured deposits. FDIC was able to do this without breaking its own finances because SVB had good assets in the form of its Treasury bond portfolio. They were just illiquid.

Question: would the same thing happen at any other bank? Well, it certainly hasn’t in the past. If you comb through the FDIC’s failed bank database you will see depositors in smaller failed banks often losing half or more of their uninsured balances. Even those who received partial recoveries took years. You see, those banks and their depositors weren’t considered “systemically important.”

Our government is giving a handful of mega-banks a massive privilege our small community banks clearly don’t get. This may produce more systemic risk, not less. I really don’t think we want to know the answer to that question, but I’ll bet someday we going to find out.

This is additionally unfair to our small local banks, which are often community pillars in places the mega-banks don’t serve. According to the FDIC’s 2020 Community Bank Survey, community banks held 30% of all Commercial Real Estate loans, despite only having 12% of the banking industry’s total assets. This doesn’t include all sorts of other loans to made to locals the large banks don’t make. We need these small banks, but then the Fed handicaps them?

Think of the uncertainty this is creating. Are your balances above $250,000 protected? Well, if they’re deposited at one of the top dozen largest banks, the answer is certainly yes. The dozen largest banks will either not be allowed to fail, or depositors will receive full coverage under that systemic importance provision.

But, what about small community banks? If yours fails, your uninsured deposits are supposed to take a haircut. And, probably a big one. Then there’s a giant gray area of medium sized banks or regional banks, which may or may not be considered systemically important. SVB wasn’t considered systemically important… until it was. No one knows what to expect.

This is simply untenable. Sure, no one wants to see anyone get hurt, but at some point, people have to bear the consequence of their decisions. If a company decides to hold $50 million or more in uninsured bank deposits—as several SVB customers did—should they be made whole when the bank fails? Is that fair to other businesses who managed their cash prudently? What incentives does it create? I don’t think we want to experience the answer to that question, nor do I think we want to live with a banking system comprised of just a dozen mega-banks. Unless you are a very large corporation, or an uber wealthy individual, we will all be standing in line, holding our cups out, until it’s our turn. It could take months to find out if we are lucky enough to borrow any money. Bottom line, after the failure of SVB, I now ponder what is considered systemically important versus what is considered systemically unfair?

I feel it’s important to note just how much power the Fed really yields. The Fed not only dictates our country’s monetary policies, but it also regulates our banks. Yes, it does works alongside the FDIC, the OCC, and the Treasury, to ensure the stability of both our banks and our banking system as a whole. In the wake SVB’s failure it seems to me this process needs improvement, or at least better communication amongst themselves inside the Fed.

Lastly, throughout my banking career, in fact my entire business career, it has always seemed to me like the Fed was fighting the last war. After the financial crisis of 2008, Congress passed the Dodd-Frank Act, which imposed many new rules and requirements, all intended to prevent another such event. And, so far it has worked: We haven’t had another subprime mortgage crisis.

But, as is always the case with regulatory legislation, Dodd-Frank has holes in it. Plus, it created unintended side effects. Not to mention a baffling application of the rules by the regulators themselves.

Dodd-Frank focused primarily on reducing bank credit risk. Specifically, the kind of mortgage lending activity which brought down a number of large institutions and countless small ones. These new requirements encouraged, or in some cases outright mandated, banks hold more Treasury bonds. In theory they would have no credit risk. Unfortunately, they never took into account the interest rate risk banks would be taking on by holding those bonds.

In truth, they did just the opposite. They let banks put long-term Treasuries and mortgages in a special regulatory bucket that didn’t require marking those assets to market against their capital base. They would only be marked to market when they actually sold. If bank management and regulators couldn’t see this as a problem, it begs the question… who’s watching the watchers.

Everything was fine, until it wasn’t. When the Pandemic hit both fiscal and monetary stimulus poured in, bank deposits ballooned, banks used those deposits to purchase treasuries and mortgage backed securities, supplies of virtually everything were greatly reduced, demand skyrocketed, and inflation soared. The result of all of this put the Fed in a bind. The obvious answer was to tighten credit by raising interest rates. However, the very same Fed who was tightening credit and raising interest rates, was also overseeing a banking industry which wasn’t prepared for this scenario.

Now the Fed has put themselves into yet another bind. Will the Fed push more banks over the edge by continuing to raise rates? Or, will the Fed not raise interest rates and risk letting inflation take off again? More to come on this when I find time to shoot a video on our economy.

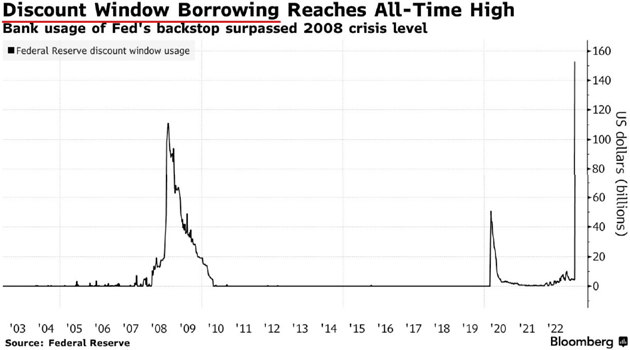
And, despite the huge increase in their balance sheet during the second week of March, I believe the Fed will continue quantitative tightening. As the chart shows, the increase came not from a stealth quantitative easing, but from banks pledging their long-term assets for new liquidity. While obviously a sign of stress—it’s also exactly how the system is designed to work in times like these.
Source: Bloomberg

And, it’s not just borrowings from the discount window. The Fed’s new Bank Term Funding Program allows banks with unrealized losses in their Treasury securities to pledge them as collateral and get cash from the Fed. Presto, instant liquidity for those who overloaded on Treasuries and/or forgot to hedge the risk. Depending on how far down the banking food chain this goes, it may solve the immediate problem. However, normal bank insolvency, like the 538 banks which have failed since 2008, will still result in bank failures. And, unfortunately, depositors at small banks will find out.

Of course, this is unfair to the prudent banks. The Fed is essentially rewarding unwise risk-taking. The fact this is done within the regulatory guidelines doesn’t mean there is no risk, just bad guidelines.

I just can’t stop thinking about that lofty Jenga tower. It’s not just banking. Commercial real estate, the markets, global trade, a clearly slowing manufacturing base, the massive rise in sovereign debt worldwide, negative growth in our money supply, and so much more. Eventually… it will be one puzzle piece too many? But, that puzzle piece isn’t going to be Silicon Valley Bank, or Signature Bank, or any of the other routine 35 to 40 bank failures a year we never hear about.

I want to thank all of you who have taken time out of your lives to listen to my thoughts. When I find the time, I will be back to share my thoughts on the economy, the RV market, and what the future may look like for both. I wish you all safe travels, and only the best. Thank you for watching.

Brett Talk: RVs, the Economy and You! SVB…Are Banks in Trouble?

Greetings National Indoor RV Centers family of customers and friends since my last video a year ago when the Fed funds rate was hovering right at zero the Federal Open Market Committee has raised the Fed funds rate nine times to its current target range of 4.75% To 5%. Well as the saying goes whenever the Fed hits the brakes someone goes through the windshield. We all know it the Fed knows it we just never know who it’s going to be until it happens. In the wake of all these rate increases by the Fed I Was preparing to share my thoughts on the current state of our economy and the RV market and where I suspect they are both headed in the future. However I have just returned home from a marathon of back to back to back motorhome rallies where for three weeks the questions posed to me about Silicon Valley Bank and how sound is our banking system?

Were relentless. And to be completely transparent it wasn’t just the plethora of questions I received during my three weeks of rallies which piqued my interest in the failure of Silicon Valley Bank or SVB for short I was already following SVB with both Intrigue and concern. Having owned a bank years ago I was following SVB with Intrigue because it wasn’t your traditional bank but I was also following it with some concern because I am a limited partner in one of those venture capital funds that did all their banking with SVB. Needless to say for all those reasons I called an audible and decided to share my musings on SVB and our banking system before sharing my thoughts on the economy in the RV market. Think of a lofty Jenga Tower when discussing complex systems like our banking system. Eventually one ever so slight miscalculation one puzzle piece too many and fatality strikes. Eventually is the key word.

Exactly which puzzle piece will do it? We can’t know ahead of time. But before the tower collapses each puzzle piece forms points of instability. Small weaknesses where a failure could begin. Sooner or later it will be one puzzle piece too many but. No one knows when or which piece will be the big one which brings the whole Tower down. These points of instability seem to be piling up lately. Last October the UK had a brief Bond crisis when some budgetary changes revealed rather questionable pension fund activities. Then the bankruptcy of crypto exchange FTX showed how supposedly trustless assets can really require a lot of trust. During the second weekend in March we witnessed the second and third largest bank failures in U.S. History Silicon Valley Bank and Signature Bank.

And yes several other Banks including First Republic and PacWest look to be very shaky as well these banks have similar features to SVB as well as exposure to crypto based businesses. However I also think these banks are very unique unicorns if you will. I don’t believe you can paint the current 4,844 FDIC insured banks in our country with the same brush as these Banks. Nor do I believe they are representative of the contagion which affected our entire Financial system back in 2008 let alone any contagion which would impact the RV industry whatsoever. Fortunately Regulators responded swiftly to stabilize both situations. Personally I believe 99% of all banks are just fine. But we should all be paying attention to make sure our bank isn’t in the 1% because important things are happening and know not for a minute do I think this is 2007 2008 all over again. But it’s also not nothing. We’ll start with what we do know.

We know SVB had problems with both their assets and their liabilities. It’s important to remember whenever we deposit our money into a bank account we are really lending our cash to the bank. It is truly a loan transaction with us as the lender and the bank is the borrower. In fact our deposits appear as liabilities on the bank’s balance sheet. This is how banking works in its simplest terms. The bank borrows money from us and then lends it to someone else. If all goes well the bank profits from the difference between the interest it pays its depositors in the interest it receives on the loans it makes. Those loans support small businesses they help consumers buy cars homeowners buy their dream homes with mortgages and a whole lot more. Banks also loan money to the federal government by purchasing treasury Securities. They don’t yield as much as a loan but they are also lower risk.

However they are not zero risk as we will see in a minute. Running a bank is truly a balancing act between the bank’s assets which are really loans and the bank’s liabilities which are really deposits. They each have different maturities. People can demand their money back at any time but the bank can’t call in its loans at least not very quickly. It works only because most people leave their balances in place most of the time. This is where having a loyal Diversified depositor base really helps reduce the risk profile of a bank. The absence of a loyal Diversified depositor base proved to be a real problem for SVB. Most of SVB’s deposits came from a relatively small group of venture capital firms Who quote recommended to the startup companies they funded to keep their cash balances at SVB. The nature of these startup companies deposits added an additional degree of difficulty to SVB’s Balancing Act.

Beyond a highly concentrated depositor base controlled by a handful of venture capital funds. Startups are just that startups companies with an idea but no Capital to bring their ideas to fruition. Venture capital funds provide their startups with all their projected cash needs right up front. Meaning on day one the startup has a pile of cash operating expenses and no revenues. The hope is revenues for their idea their new product will grow to meet and exceed their operating expenses and thereby start producing a profit. It’s not uncommon for this to take years. It took over nine years from its founding for Amazon to turn its first profit in Amazon’s 58th quarter of existence it finally made a profit larger than its previous 57 quarters combined that’s 14 years and two quarters after startup. Here are a few more companies.

We all know it was five years before FedEx was able to turn a profit in seven years before ESPN became profitable from its founding it was 17 years before Tesla made its first dime. From their founding to profitability startup companies are burning through the cash they were funded with at startup. Venture capital funds project what they believe the burn rate of their startups will be until they reach profitability. And assuming their ideas proved to be economically viable. They fund their startups with that Capital right up front and in turn those startups deposit their funds in whichever Bank they’re sponsoring venture capital fund recommends. In addition to their highly concentrated depositor base of venture capital funds. SVB had to also contend with the burn rate of the startups these firms had funded which now comprise their depository base. Clearly this was far from a traditional depository base for a bank.

As a part of the macro slowdown in 2022 which slowed down was the intended result of the Fed raising interest rates the burn rates of these startups actually accelerated. SVB poorly forecasted The Accelerated burn and the resulting drawdown needs of their depositors which resulted in SVB not having the liquidity to pay them all. What SVB did have was a lot of longer-term Treasury bonds and mortgage-backed securities it had purchased when their deposits ballooned in 2020 and 2021 which was before the Fed started raising interest rates in March of 2022. If you remember from my RVs, the Economy and You update to part one video from last year when interest rates rise the market value of bonds Falls. Which isn’t a problem if you can hold the bonds to maturity. However it can become a big problem if you need to sell them in order to cover your depositors withdrawals.

Rising interest rates put SVB in a tough spot which got tougher as depositors withdrew their money in the weeks leading up to SVB’s failure on March 10 2023. Here is an excerpt from my video last year which is truly appropriate in SVB’s case. I’d like to start by quoting two lines from Ernest Hemingway’s novel The Sun Also Rises we’re in Bill asks how did you go bankrupt to which Mike responds two ways gradually then suddenly. SVB’s failure started gradually by poorly forecasting their depositors burn rate which is best explained by SVB’s former president in his letter to investors and I quote while venture capital deployment has tracked our expectations client cash burn has remained elevated and increased further in February resulting in lower deposits than forecasted when we see a return to balance between Venture investment and cash burn we will be well positioned to accelerate growth and profitability end quote.

He also noted quote SVB is well capitalized end quote. SVB was forced to sell some of their treasuries and mortgage-backed securities in order to fund these withdrawals. With each sale of their treasuries. SVB was forced to recognize the inherent Market losses created by. Rising interest rates over the past year. SVB’s portfolio of treasuries was yielding an average of 1.79% Per annum which was Far Below the 10-year treasury yield of 3.9% Per annum. These sales forced SVB to recognize a $1.8 Billion loss which it would need to replace through raising more Capital by selling more shares in the bank. Late in the day on Wednesday March the 8th SVB spooked investors and depositors with a belated attempt to raise additional Capital by announcing the sale of $2.25 Billion in common equity and preferred convertible stock to replace the capital it had just lost.

SVB stock ended the day down 60% as investors fretted further deposit withdrawals may push the bank to raise even more capital. In what will probably turn out to be the most ill-advised conference call in the history of banking. In a failed attempt to head off a run on his bank the president of SVB held a conference call with the bank’s 12 largest venture capital funds at 11 30 a.M Pacific Standard Time on Thursday March the 9th. The purpose of his call was to reassure the bank’s largest depositors their deposits were safe the bank was healthy and in not so many words he essentially conveyed the bank could withstand anything except a run on the bank. Well. As it turned out the Dozen venture capital funds weren’t going to SVB’s president instructed them to remain calm three times on the call. Within 30 minutes of the call ending $42 billion of withdrawal requests hit the bank’s wire desk.

That bears repeating $42 billion of SVB’s $175 billion in total deposits had just requested their money back. The bank did manage to fulfill the $42 billion in withdrawal requests and then they promptly closed the bank early which led to the lines of people we’ve all seen pictures of as venture capital funds instructed their companies to go to the bank to withdraw their money in person. However Thursday’s $42 billion in withdrawals pales in comparison to what was about to happen on the morning of Friday March the 10th. Michael Barr Vice chair for supervision at the Federal Reserve testified before the Senate Banking Committee and I quote that morning the bank let us know that they expected the outflows to be vastly larger based on client requests a total of $100 billion was scheduled to go out the door that day end quote.

Consequently SVB never opened on Friday as the combined withdrawal figure of $142 billion represented a staggering 81% of SVB’s $175 billion in deposits. Think about that $142 billion in withdrawals in less than 24 hours. Which is. Why the FDIC jumped in. The dizzying pace at which money left SVB shows just how quickly Bank runs can happen with the technology of today’s world. Social media heightens panic and online banking allows for quick transactions. The speed at which SVB failed is unique and. To highlight this point think about this 538 banks have failed since 2008. And yet few of us knew about them life went on as normal. But $142 billion in under 24 hours severely limited the FDIC’s options and brought with it a lot of publicity. I readily admit I wasn’t a fan of how the Fed handled the bailouts of banks in the 2008 crisis. But I do believe they did it correctly this time.

While you may or may not be a fan of SVB’s customers. Tech startups they were and are very important to the U.S. Economy. We need them I believe they are truly systemically important. The FDIC gave SVB’s customers full access to their deposits so they made payrolls and life went on. I believe this was appropriate and please let me explain. The world’s five most devastating financial crises are the credit crisis of 1772 the Great Depression of 1929 to 1939 the OPEC oil price shock of 1973 the Asian crisis of 1997. And the financial crisis of 2007-2008. I have lived through three of those five crises. But the financial crisis of 2007-2008 really stands out and not because it’s the most recent stands out because of how it was handled the Troubled Asset Relief Program better known by its acronym TARP was instituted by the U.S. Treasury following the financial crisis of 2007-2008.

TARP stabilized our financial system by having the government purchase mortgage-backed Securities and Bank stocks. That’s right the government purchased equity in Banks and other financial institutions. From 2008 to 2010 TARP invested $426.4 Billion in Banks and other financial institutions and recouped $441.7 Billion in return. But part of what made TARP so controversial was the shareholders were not wiped out nor were any people fired. That is. Why I wasn’t a fan of how the bailed the banks out in 2008. But this time around unlike 2008 the FDIC did wipe the shareholders out and they did fire Senior Management of the bank. When you mess up that spectacularly you should be fired and honestly I will say the same thing about Federal regulators and their ridiculous stress tests. It’s hard for me to believe they could have truly been that blind.

As pointed out in the Wall Street Journal on March 15th even if mid-sized Banks had been subjected to the same scrutiny as large Banks it’s very doubtful it would have prevented SVB’s failure. Why because the stress tests failed to Encompass the very scenario which ultimately led to SVB’s demise large and Rapid increases in interest rates in its February 2022 stress test scenarios the feds quote severely adverse scenario end quote ask Banks to assess the riskiness over a three-year Horizon assuming the three-month treasury stayed near 0% while the 10-year treasury declines to three quarters of 1% during the first three calendar quarters of 2022. Think about that for a minute in February 2022 the Fed instructed Banks to assume 0% interest when creating the worst case scenarios and then starting the very next month in March of 2022 the Fed promptly raises rates five times to 4.5% Interest by the end of 2022.

The biggest rate increase in a single year since 1980. Then in February of 2023 when the three-month treasury was already yielding 4.5% The Fed shockingly instructs Banks to assume the three-month treasury falling to near 0% by the third quarter in the 10-year treasury falling to one half of 1% by the second quarter in their worst case scenarios. This truly makes reason stare is this how anyone who is warm and has a pulse would project and prepare for a worst case scenario by pretending they’re really not raising interest rates is this truly how they’re going to regulate our banks talking out of both sides of their mouths. Throughout my business career I’ve always believed no enemy is worse than bad advice. The Fed’s 2023 severely adverse scenario assumptions bear no relationship to reality. Do the Fed’s bank regulators not talk with each other or at a minimum at least read about what is going on with their own monetary policies.

They have been raising rates for a year. The regulatory Executives who somehow managed to overlook this should be fired just like the Senior Management of SVB was. But we all know that’s not going to happen. Passing additional laws and regulations isn’t going to help if The Regulators are incompetent. There were more than enough laws and regulations to have prevented this. In my opinion firing the Senior Management at SVB is just a start in cleaning house. Moving on. I don’t know whether this is fascinating or truly troubling but 94% of the deposits at SVB were above the $250,000 FDIC Insurance limit and thereby uninsured. The $250,000 Insurance amount was certainly no secret is plastered all over Bank walls and it appears in almost every account document anyone signs. It was crystal clear larger balances were at risk if the bank failed.

But SVB depositors some of them the most sophisticated investors on the planet simply didn’t seem to care or believe the limit didn’t apply to them. As it turned out it didn’t. Many if not most banks offer an insured cash sweep or ICS service I know all of our banks offer it. ICS accounts extend FDIC insurance by breaking up large cash deposits and then Distributing the smaller amounts to multiple Banks ICS accounts simply allow businesses access to FDIC coverage above the standard $250,000 limit. It’s a safe and simple thing to sweep excess amounts and bring them back in as needed to clear checks. In today’s world keeping millions of uninsured dollars in the same bank just makes no sense. Yet it was very common at SVB. And it wasn’t just SVB. Even our largest banks have more uninsured than insured deposits.

And yes from the chart you can see how SVB led the way with 94% of their deposits being uninsured 20% more than the next closest bank which happens to be the international Behemoth Citibank. But let’s put this into perspective Citibank has 673 locations in the United States in 1800 branches scattered throughout 160 other countries versus SVB with just 17 branches. I can easily understand. Why depositors in other countries would care far less about the FDIC Insurance limits and our domestic depositors. My point SVB was a unique Bank. It was a unicorn that wasn’t representative of our banking system or the contagion which affected our entire Financial system back in 2008. These excessively High uninsured balances haven’t always been the case. Look at this chart from Yardeni QuickTakes comparing insured and uninsured deposits for all U.S banks with the current $250,000 deposit insurance limit U.S banks had $10.5 Trillion in uninsured deposits halfway through 2022 versus only $7.4 Trillion insured.

In fact the majority of deposits have been uninsured for a decade now. But notice how the line bends sharply upward in 2020. Why well it’s because it coincides with the Fed stimulus plus all the various COVID fiscal programs. However there was and there still is nothing requiring people to keep all that money in Banks. This certainly seems like a problem to me. In the case of SVB regulators used a systemic risk emergency Clause to cover otherwise uninsured deposits FDIC was able to do this without breaking its own finances because SVB had good assets in the form of its treasury bond portfolio they were just illiquid. Question would the same thing happen at any other bank? Well it certainly hasn’t in the past. If you comb through the FDIC’s failed Bank database you will see depositors in smaller failed Banks often losing half or more of their uninsured balances. Even those who receive partial recoveries took years.

You see those Banks and their depositors weren’t considered systemically important. Our government is giving a handful of Mega Banks a massive privilege our small Community Banks clearly don’t get. This may produce more systemic risk not less. I really don’t think we want to know the answer to that. Question but I’ll bet someday we’re going to find out. This is additionally unfair to our small local banks which are often Community pillars in the places Mega Banks don’t serve. According to the FDIC’s 2020 Community banking survey Community Banks held 30% of all commercial real estate loans despite only having 12% of the banking industry’s total assets. This doesn’t include all sorts of other loans made to locals the large Banks don’t make. We need these small Banks but then the Fed handicaps them. Think of the uncertainty this is creating are your balances above $250,000 protected?

Well if they’re deposited one of the top dozen largest banks the answer is certainly yes the Dozen largest banks will either not be allowed to fail or depositors will receive full coverage under that systemic importance provision. But what about small Community Banks? If yours fails your uninsured deposits are supposed to take a haircut and probably a big one. Then there is a giant gray area of medium-sized Banks or Regional Banks which may or may not be considered systemically important. SVB wasn’t considered systemically important until it was. No one knows what to expect. This is simply untenable. Sure no one wants to see anyone get hurt. But at some point people have to bear the consequences of their decisions. If a company decides to hold $50 million or more in uninsured Bank deposits as several of SVB’s customers did should they be made whole when the bank fails? Is it fair to the other businesses who manage their cash prudently?

What incentives does this create? I don’t think we want to experience the answer to that. Question. Nor do I think we want to live with a banking system comprised of just a dozen megabanks. Unless you are a very large corporation or an uber wealthy individual we will all be standing in line holding our cups out until it’s our turn it could take months to find out if we are lucky enough to borrow any money. Bottom line after the failure of SVB. I now Ponder what is considered systemically important versus what is considered systemically unfair. I feel it’s important to note just how much power the Fed really wields. The Fed not only dictates our country’s monetary policy but it also regulates our banks. Yes it does work alongside the FDIC the OCC and the treasury to ensure the stability of both our banks and our banking system as a whole.

In the wake of SVB’s failure it seems to me this process needs Improvement or at least better communication amongst themselves inside the Fed. Lastly throughout my banking career in fact my entire business career it has always seemed to me like the Fed was fighting the last war. After the financial crisis of 2008 Congress passed the Dodd-Frank Act which imposed many new rules and requirements all intended to prevent another such event. And so far it’s worked we haven’t had another subprime mortgage crisis. But as is always the case with regulatory legislation Dodd-Frank has holes in it plus it created unintended side effects not to mention a baffling application of the rules by the regulators themselves. Dodd-Frank focused primarily on reducing Bank credit risk specifically the kind of mortgage lending activity which brought down a number of large institutions and countless small ones. These new requirements encouraged or in some cases outright mandated Banks hold more treasury bonds.

In theory they would have no credit risk. Unfortunately they never took into account the interest rate risk Banks would be taking on by holding those bonds. In truth they did just the opposite they let Banks put long-term treasuries and mortgages in a special regulatory bucket that didn’t require marking those assets to Market against their Capital base. They would only be marked to Market when they actually sold. If Bank management and Regulators couldn’t see this as a problem. It begs the. Question who’s watching the Watchers? Everything was fine until it wasn’t. When the pandemic hit both fiscal and monetary stimulus poured in. Bank deposits ballooned banks used those deposits to purchase treasuries and mortgage-backed securities supplies of virtually everything were greatly reduced demand skyrocketed and inflation soared the result of all of this put the Fed in a bind. The obvious answer was to tighten credit by raising interest rates.

However the very same fed who was tightening credit and raising interest rates was also overseeing a banking industry which wasn’t prepared for this scenario. Now the Fed has put themselves into yet another bind. Will the Fed push more Banks Over the Edge by continuing to raise rates or. Will the Fed not raise interest rates and risk letting inflation take off again. More to come on this when I find time to shoot a video on our economy. And despite the huge increase in their balance sheet during the second week of March I believe the Fed will continue quantitative tightening. As the chart shows the increase came not from the stealth quantitative easing but from Banks pledging their long-term assets for new liquidity. While obviously a sign of stress it’s also exactly how the system is designed to work at times like these. And it’s not just borrowing from the discount window.

The Fed’s new Bank Term Funding Program allows banks with unrealized losses in their treasury Securities to pledge them as collateral and get cash from the Fed. Presto instant liquidity for those who overloaded on treasuries and/or forgot to hedge the risk. Depending on how far down the banking food chain this goes it may solve the immediate problem. However normal Bank insolvencies like the 538 Banks which have failed since 2008. Will still result in bank failures and. Unfortunately depositors at small banks will find out. Of course this is unfair to The Prudent Banks. The Fed is essentially rewarding unwise risk-taking. The fact this is done within regulatory guidelines doesn’t mean there’s no risk just bad guidelines. I just can’t stop thinking about that lofty Jenga Tower. It’s not just banking commercial real estate the markets global trade a clearly slowing manufacturing base the massive rise in sovereign debt worldwide negative growth in our money supply and so much more.

Eventually it will be one puzzle piece too many. But that puzzle piece isn’t going to be Silicon Valley Bank or Signature Bank or any of the other routine 35 to 40 bank failures a year we never hear about. I want to thank all of you have taken time out of your lives to listen to my thoughts. When I find the time I will be back to share my thoughts on the economy the RV market and what the future may look like for both. I wish you all safe travels and only the best thank you for watching.

2023 Turismo-ion by Grech RV

Looking for a top-of-its-class B van? Look no further than Grech RV

When it comes to Class B RVs (a.k.a. Adventure Vans, Camper Vans, B-Vans, etc.), there is certainly no shortage of options. Grech RV, however, has set itself apart from the competition through its dedication to superior craftsmanship, extreme attention to detail and focus on functionality. 

2023 Turismo-ion Features

Coming in at 19’ long, the Turismo-ion offers a smaller footprint than Grech’s flagship Strada line, providing greater overall agility while sacrificing none of Grech’s acclaimed luxury. Built on the Mercedes-Benz 2500 Sprinter chassis, it is available in either 2- or 4-wheel drive (4×4 shown in video, below) and boasts a 6-cylinder diesel engine, making it able to tackle any terrain. These foundational features point to the quality of engineering and durability right from the start, setting the stage for unparalleled fit and finish. 

Ever-present in Grech RV coaches are attention to detail and exquisite craftsmanship, exemplified in the Turismo through its Black Rhino alloy wheels, power entry step, concealed stainless steel utility center, power awning with wind sensor and custom fiberglass body kit.


Grech RV’s Energy-Efficiency

The Turismo-ion (and all Grech RV models) utilizes the Timberline System, a diesel fuel-fired heating system that provides a continuous flow of hot water and heat to the motorhome. Additionally, the 280 AMP high-output auxiliary alternator and Wakespeed Regulator charge the vehicle’s lithium-ion batteries while at idle, eliminating all worry while boondocking and during extended adventures. 


2023 Turismo-ion Interior

The Turismo-ion comfortably sleeps two and can accommodate up to four passengers in its spacious interior, which features an integrated power-management system that allows passengers to easily control lighting and temperature. The 200-watt solar power system offers added power to the LED accent lighting and induction dual-burner stovetop, ensuring you’ve got the capacity to live your life wherever you are and whenever you need it. 

For more on Grech RV, take a look at Angie’s tour of the Grevh RV factory! You’ll learn more about their history, exquisite fit and finish, and the meticulous processes that go into every coach they build, including their flagship Strada series.  And don’t forget that NIRVC proudly carries Grech RVs! Take a look at our current inventory, HERE. 

How To Power Your RV

How to Power Your RV

Your RV’s 120 volt electrical system is fed through a central distribution panel where all of the circuit breakers are located. In order to power this panel from two different power sources we can choose one of two methods. The first is the more cost effective and least costly and is commonly used in lower cost travel trailers. That method entails hard wiring a power cord to the breaker panel’s inputs. When not plugged into shore power this cord can be plugged into a generator set outlet to provide power to the RV’s electrical systems. While this method is inexpensive, it’s less convenient because you have to physically switch the plug from the shore power receptacle to the generator receptacle. The second method is to install an automatic transfer switch.

Automatic transfer switch

Manual vs Automatic Transfer Switches

Manual transfer switches need to be manually switched by moving the switch lever on the box and are uncommon in a motorized RV. Automatic transfer switches commonly used in an RV will do this automatically and are logic controlled to switch under a given set of conditions. Generally automatic transfer switches will default to the generator inputs and are mechanically held. Once shore power is present the magnetic coils will pull the switch’s contact relays over to the shore power side. This is why you typically hear that clunk when the switch engages shortly after connecting to shore power. As soon as the shore power is no longer present the switch will revert back to its generator priority position.

Generators for Your RV

Sometimes the 120 volt devices in your motorhome need to be powered when you are not plugged into a campground pedestal, frequently referred to as shore power. When shore power is unavailable, the on-board generator set can be used to power these devices. Generators can be used in a number of situations, such as camping in remote areas where access to power is not available. A number of systems, such as lighting, water pumps and fans, are powered by your 12 volt battery. However, there will come a time when these batteries need to be recharged. The on-board generator can be used to power the coach’s battery charging system in the absence of shore power. Another use for generators is to power the rooftop air conditioners to make for a more comfortable motorhome interior in hot weather.

Generators for Gasoline Engines

Gasoline powered Class A motorhomes will be equipped with a generator powered by a gasoline engine. The generator shares the same fuel tank as the vehicle engine but uses a separate fuel pickup within that tank. Usually these pickup tubes are cut short so that the generator will not run if the fuel level gets below a ¼ tank but this amount can vary from one manufacturer to the next. The reason for this is so that you can’t totally drain your fuel tank while dry camping. The ¼ tank remainder ensures that you will always be able to start your RV’s engine and drive to a refueling location. These generator sets are designed to slide into a basement compartment that is designed for that purpose so access to the controls and engine service points is done through the removable side cover on the generator, which also serves to contain the cooling airflow and add additional sound deadening capability.

Onan Quiet Power diesel generator

Generators for Diesel Engines

Diesel powered generators can be found on motorhomes that are powered by diesel engines. Some of the entry level class A diesels are really front engine gasoline chassis with a diesel engine in place of a gasoline engine. Also, many smaller B+ and Super C motorhomes are now being made with small diesel engines. In this case the diesel powered generator will be fairly small (in the 4 KW to 7 KW range) and will be mounted in a side compartment in the same fashion as the gasoline powered generators. On a rear engine diesel pusher, the front of the coach is clear of engines and radiators. In this case you’ll find a diesel powered generator that is mounted in the front cap on a set of slide rails. The generator can be slid forward out of the coach to allow better access for servicing the unit. These units generally start at around 7,500 watts and run up to 10,000 or 12,500 watts in size. 

Some older motorhomes used a propane powered generator that ran off the RV’s on-board LP tank. However, these are rare and less desirable because the limited capacity of the propane tank didn’t give the generator a very long running time before the LP tank was empty. Used coaches with propane powered generators are very hard to sell and their resale value reflects this.

In-Phase vs Split-Phase Generators 

Generators that are rated up through 8,000 watts are usually single pole 120 volt-only generators, referred to as “in-phase” generators because both windings are in the same phase. Larger generators, 10,000 watts and up are two pole split-phase 120/240 volt generators with a center tap neutral. Because motorhomes rarely have any 240 volt appliances you may think that this arrangement isn’t needed. But if you refer back to our split phase 120/240 diagram you’ll recall that each phase has a given amount of amps available. That’s what allows you to balance your load and eliminate the heavy wiring required for a 10KW generator, which would output 83.33 amps if it was an in-phase design. Note that a 50 amp electrical service is equivalent to 12,000 watts, which is the size generator required if you needed to supply a full 50 amps to your RV’s breaker panel.

What to Consider When Choosing a Generation System 

Small portable generators tend to be noisy because an engine running at 3,600 RPM isn’t very quiet. They were designed to be light and portable. In a motorhome this isn’t important because the generator doesn’t need to be lifted because it will be mounted into the RV. What is important is the noise level. If we add a second set of field coils to our generator, we will double the frequency to 120 Hz when running at 3,600 RPM, which isn’t good and will burn up our electrical devices. But if we take that same 4 pole generator and slow it down to 1,800 RPM we will still have 60 Hz. It’s just that we are passing twice as many magnets during the same revolution so by reducing the number of revolutions by half we will still maintain 60 Hz.

This is the way many RV generators are set up. The 1,800 RPM speed of the engine allows for quieter operation. Because we don’t have to lift this generator we can also add a nice large muffler to it. The big drawback is that we have to use a larger engine. A small 8 HP engine is capable of creating 3,500 watts at 3,600 RPM but when you slow it down to 1,800 RPM it will only put out around 5 HP, which isn’t enough. By going with a 12-14 HP engine, we will still have 8 HP available at 1,800 RPM to then make our 3,500 watts of power. This means that the engine will be physically larger, weigh more, be quieter and more durable, and cost more than a smaller engine that is running higher revs. But the gains are well worth it in an RV application. Large utility power plants carry this even further and can use as many as 24 field coils in their generation systems so that they only have to turn 300 RPM. Less RPMs means greater life but more weight and size, while less magnets means less weight and size but greater speed and wear.

Winnebago Solis Special

Winnebago Solis as low as $599/mo*

We are offering a fantastic special on any in-stock Winnebago Solis now through May 1! Browse our qualifying Winnebago Solis inventory today.
Take a walkthrough of a Winnebago Solis with our very own RV expert, Angie Morell.

*Terms available on approved credit only to very well-qualified applicants. Monthly payment example based on MSRP of $87,521 with 10% down payment. Individual dealer prices, other terms and offers may vary. Must purchase from dealer’s stock and terms are subject to availability. Void where prohibited. Offer ends 5/1/2023 and you must take delivery prior to expiration of offer. See participating NIRVC Dealer for complete details. Product shown may not reflect actual inventory in stock.

Winnebago Revel Special

Winnebago Revel as low as $999/mo*

We are offering a fantastic special on any in-stock Winnebago Revels now through May 1! Browse our qualifying Winnebago Revel inventory today.

 Take a walkthrough of a Winnebago Revel with our very own RV expert, Angie Morell.

*Terms available on approved credit only to very well-qualified applicants. Monthly payment example based on MSRP of $209,516 with 10% down payment. Individual dealer prices, other terms and offers may vary. Must purchase from dealer’s stock and terms are subject to availability. Void where prohibited. Offer ends 5/1/2023 and you must take delivery prior to expiration of offer. See participating NIRVC Dealer for complete details. Product shown may not reflect actual inventory in stock.